What if the “lowball” offer you’re worried about is actually a precise mathematical equation designed to provide you with the fastest possible exit? It’s natural to feel a sense of dread when you look at a property that needs tens of thousands in repairs you simply cannot afford. You want a fair deal, but the jargon and hidden numbers can make the process feel like a black box. Understanding how cash home buyers determine offer price is the first step toward regaining control of your situation and moving forward with confidence.
We believe that transparency is the only way to build a real partnership. You deserve to know exactly how the math works so you can decide what’s best for your family without any high-pressure tactics. In this article, we’ll reveal the exact formulas used by professionals, including the 70% rule and the reality of After Repair Value in the 2026 market. We’ll also explore how holding costs and current renovation averages, which now range between $50,000 and $80,000, impact the final number. By the end, you’ll have a clear roadmap of the math behind the offer and the certainty that comes with a fast, certain exit strategy.
Key Takeaways
- Learn how professional buyers move beyond simple rules of thumb to create a fair offer based on your home’s unique potential.
- Gain a clear look at how cash home buyers determine offer price by balancing the After Repair Value with the actual cost of renovations and holding fees.
- Discover how creative finance solutions can often provide a higher payout than a standard cash offer when your situation requires more flexibility.
- Understand why the final amount you keep from a cash sale often rivals the net proceeds of a traditional listing after you account for commissions and repairs.
- Identify the hidden costs like insurance and taxes that investors must calculate to ensure a certain, fast closing for you.
Beyond the Lowball Myth: What a Cash Offer Really Represents
Many homeowners assume a cash offer is simply a discounted price for a quick sale. However, viewing it this way misses the actual mechanics of the transaction. A cash offer is primarily a liquidity-driven event. It’s a trade-off where the buyer takes on all the market risk, repair costs, and holding expenses in exchange for giving the seller immediate access to their equity. You aren’t just selling a house; you’re purchasing speed and the removal of a burden that might otherwise take months to resolve.
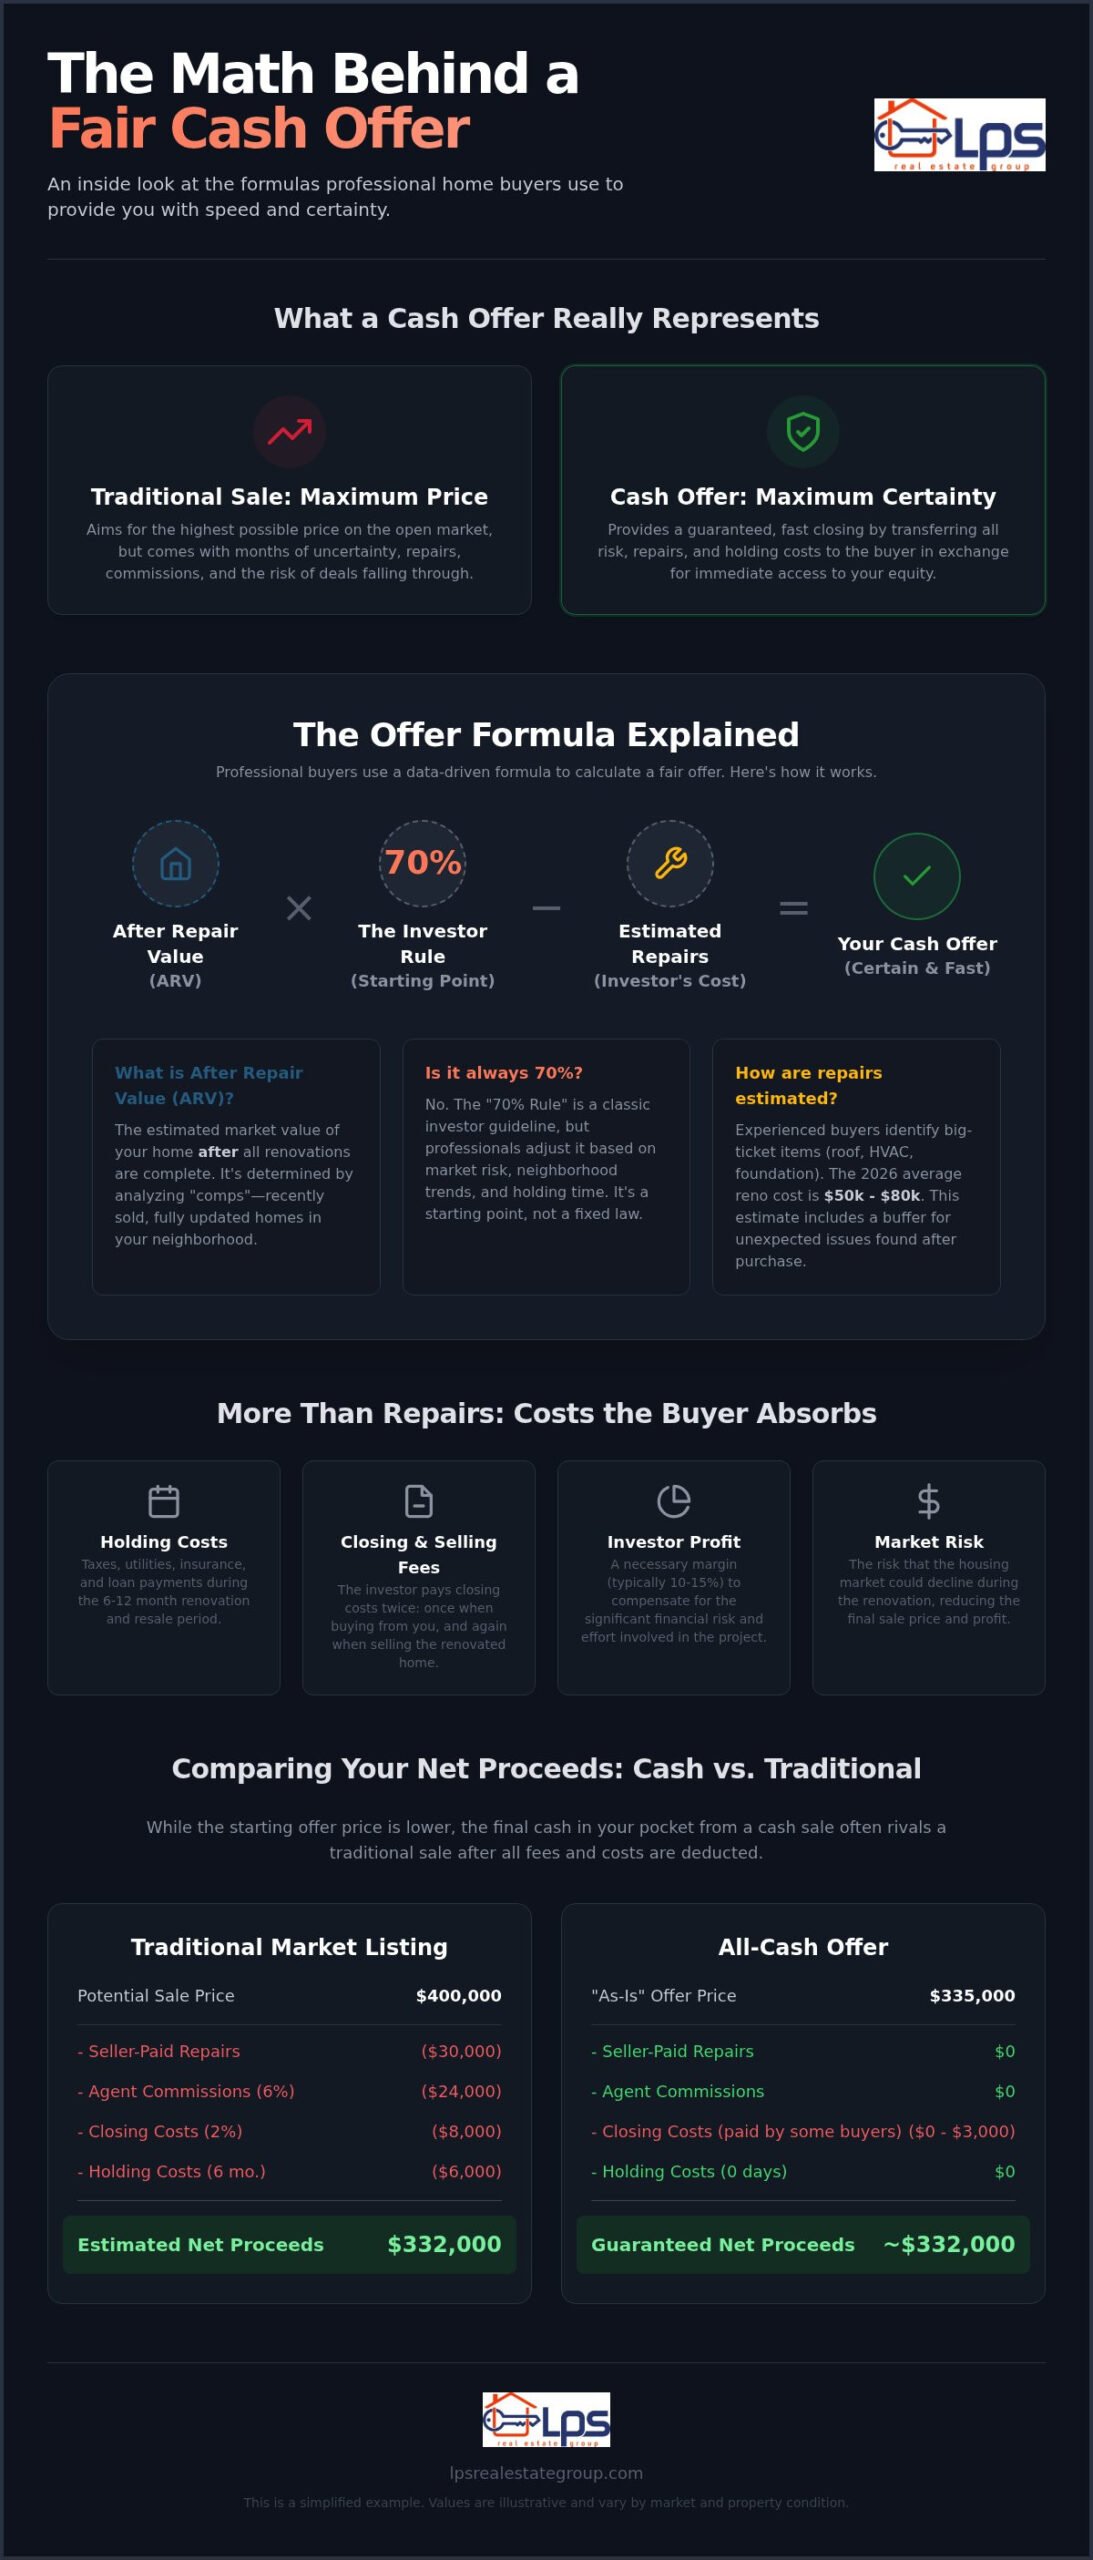
The “70% rule” is a phrase often tossed around in investing circles. It suggests that a buyer should offer 70% of the home’s future value minus repair costs. While this serves as a rough starting point, it’s an oversimplification in today’s market. Professional buyers look at much more than a flat percentage. They evaluate specific neighborhood trends, the rising cost of materials, and the time it takes to complete a project. Understanding how cash home buyers determine offer price requires looking at the specific math of your property rather than relying on a generic rule of thumb. This creates a fundamental trade-off. You’re choosing between the “Maximum Price” a retail buyer might pay after months of staging and negotiating, and the “Maximum Certainty” of a cash transaction that removes the risk of a deal falling through.
The Problem with Traditional Market Appraisals
A standard Real estate appraisal is designed for a bank’s peace of mind. It assumes the house is in “retail” condition and that a buyer will secure a 30-year mortgage. When a property needs significant work, it often becomes ineligible for traditional financing. This shrinks the pool of potential buyers to those who can pay cash. Because “as-is” properties carry hidden risks, the valuation must account for the unknown issues that a bank-funded buyer wouldn’t even be allowed to take on. The timeline also matters. A distressed timeline requires a buyer who can move in days, not months, which changes how the property’s immediate value is calculated.
Transparency as the Foundation of Fairness
At LPS Real Estate Group, we believe that fairness starts with an open book. You shouldn’t have to guess why a number is what it is. A reputable buyer will explain the math, showing you exactly what the repair estimates look like and how market fluctuations affect the bottom line. We move away from high-pressure tactics. Instead, we act as a trusted advisor. Our goal is to provide a sense of relief by offering a clear, certain path forward, even in complex situations like probate or foreclosure where traditional math might not apply. Because we specialize in creative finance solutions, we can often look past a simple “take it or leave it” cash offer to find a tailored exit strategy that works for your specific needs.
Calculating After Repair Value (ARV) and Renovation Costs
To understand how cash home buyers determine offer price, you must look at the property through the lens of its future potential. The process begins with the After Repair Value. We don’t look at what the house is worth today in its current state; we look at what it could be. By analyzing “comps,” which are recently sold homes nearby in top-tier condition, we establish a target price. This establishes the ceiling. It’s a data-driven starting point that ensures the math is grounded in the actual market reality of your neighborhood.
Professional buyers use these comparable sales to project value with high precision. We look for homes sold within the last six months that share your property’s square footage and layout. This approach removes the guesswork. It ensures the offer reflects what buyers are actually paying for renovated homes right now. It’s about finding a fair middle ground that respects the home’s potential while acknowledging the significant work required to get there.
Estimating renovation costs without a month-long inspection period is where experience matters most. Most professional buyers can walk through a home once and identify big-ticket items like HVAC, roofing, and foundation needs. In 2026, the average cost to flip a house is between $50,000 and $80,000. We factor in an “Investor Discount” to account for the risk of unknown structural issues. If we find a cracked pipe or hidden electrical problem after the sale, that’s our financial burden, not yours. This risk-sharing is a key part of how cash home buyers determine offer price while ensuring you receive a certain, fast closing.
How We Find Your Home’s “Highest and Best Use”
We analyze what a fully renovated version of your home would sell for today by studying neighborhood standards. If every home on your block has quartz countertops and finished basements, our renovation budget must include those features to hit the target price. We distinguish between cosmetic updates like paint and major structural overhauls. A house that only needs flooring will naturally receive a higher offer than one requiring a total gut renovation. Our goal is to find the most efficient path to bringing the property back to its highest potential.
The Reality of “As-Is” Buying
One of the biggest points of relief for our clients is skipping the “MLS-ready” preparation. You don’t have to worry about cleaning, trash removal, or making basic repairs. We handle the heavy lifting. ARV is the projected sale price after all improvements and renovations are complete. By taking the property as-is, we save you the stress of managing contractors or spending your own savings on a house you’re trying to leave. To further simplify your move, you can learn more about Coastal Legacy Estate Sales for help with cleanouts and property liquidation. If you want to see how these factors apply to your situation, you can get a clear property evaluation to understand your options.
While the After Repair Value and renovation budget are the largest pieces of the puzzle, they don’t tell the whole story. A vital part of how cash home buyers determine offer price involves looking at the “soft costs” that accumulate after the sale. These are the expenses that keep a project running but don’t add physical value to the structure. When you sell to a professional buyer, you’re transferring these financial burdens to them, allowing you to walk away with a clean break.
The Hidden Expenses of Property Ownership
Every day a house sits vacant, it costs money. Investors refer to this as the “burn rate.” It’s the total of all non-renovation expenses required to keep the property legal and protected. Research shows that average holding costs for a flip in 2026 range between $1,500 and $3,000 per month. These costs include several recurring items:
- Property taxes and local assessments.
- Homeowners insurance premiums for vacant properties.
- Essential utilities like electricity, water, and climate control.
- HOA fees or neighborhood dues.
Because these costs eat into narrow margins, the speed of the transaction is paramount. When we can close quickly, we reduce the total holding cost burden. This efficiency is often reflected in the fairness of the offer we provide. We subtract these projected expenses from the ARV to ensure the math remains sustainable throughout the life of the project.
Closing Costs and Commissions
One of the most significant differences between a cash sale and a traditional listing is who pays the transaction fees. In a typical market sale, sellers can expect to pay between 6% and 10% of the home’s price in total closing costs. This includes the standard 6% agent commission and another 1% to 3% in title insurance, escrow fees, and transfer taxes. With a cash offer, those commissions disappear. Professional buyers usually cover the seller’s side of the closing costs, meaning the number on your offer is much closer to the actual amount you take home. You can find a detailed comparison in our Selling Your House As-Is: The Complete 2026 Homeowner’s Guide.
Finally, we must account for market risk. A typical renovation and resale cycle takes three to six months. During that time, market conditions can shift. With 30-year fixed mortgage rates currently averaging 7.09%, any sudden volatility can impact the final retail buyer’s ability to purchase the home. We build a small buffer into our math to protect against these price drops. This ensures that even if the market dips while we’re working on the house, your certain exit remains secure.
Creative Finance: How Non-Cash Structures Can Increase Your Offer
Sometimes, a standard cash offer isn’t the right fit for your financial goals. While we’ve discussed how cash home buyers determine offer price based on repair costs and market risk, there’s another path that often results in a higher purchase price. Creative finance allows us to move beyond the limitations of a single, discounted cash number. By using structures like “Subject-To” or seller financing, we can solve complex problems that a simple check can’t always address. This approach changes the math because it focuses on the cost of capital and the terms of the deal rather than just the immediate liquidity.
Subject-To involves a buyer taking over your existing mortgage payments. In an era where 30-year fixed mortgage rates are averaging 7.09%, your existing lower-rate loan is a valuable asset. If we can step into a 3% or 4% interest rate, our monthly costs are lower than if we used a new hard money loan. We can often pass those savings directly to you in the form of a higher purchase price. Seller financing, on the other hand, turns you into the bank. You receive a monthly check over time rather than a single lump sum. This is a powerful tool for those who don’t need all the cash at once but want to maximize their total return on the property.
Solving the “Low Equity” Dilemma
If you owe almost what the house is worth, a traditional cash offer might require you to bring money to the closing table. That’s a stressful situation nobody wants to face. Creative finance provides a path to selling without that financial burden. By taking over the debt, we can often provide a certain exit that protects your credit and removes the weight of a property you can no longer manage. It’s about finding a way to say “yes” when the traditional math says “no.” You can learn more about these options in our guide to Creative Real Estate Exit Strategies: A Homeowner’s Guide to Certainty in 2026.
The Benefits of Monthly Cash Flow vs. A Lump Sum
For some homeowners, a steady stream of income is more valuable than a one-time payment. This approach is particularly helpful for probate situations or inherited properties where the goal is long-term stability rather than immediate cash. At LPS Real Estate Group, we act as a compassionate expert. We listen to your needs first and then engineer a solution that fits your specific circumstances. We don’t just look at the math of the house; we look at the math of your life. If you’re facing a complex situation like a tax lien or a pending foreclosure, contact us to discuss a tailored exit strategy that works for you.
Comparing Net Proceeds: Cash Offer vs. Traditional Market Listing
It’s easy to get caught in the “Sticker Price” trap. When you see a high number on a traditional market appraisal, it feels like the obvious choice. However, the listing price is never what you actually keep. To truly understand how cash home buyers determine offer price, you have to compare the final net proceeds of both paths. A cash offer isn’t a discount on your home’s value; it’s a calculation of what you’ll actually have in your bank account once the dust settles. By looking at how cash home buyers determine offer price through this lens, you see that the value lies in the speed and reliability of the exit.
The Math of a Traditional Sale
A traditional sale involves a long list of deductions that many homeowners overlook until they’re sitting at the closing table. The formula is straightforward but often surprising: Listing Price minus Commissions, Repairs, Closing Costs, and Carrying Costs equals your Net Proceeds. In the 2026 market, you can expect to pay a 6% agent commission plus another 1% to 3% in seller closing costs. Then there’s the “inspection renegotiation.” After a buyer’s inspection, they often demand thousands in credits for repairs you didn’t even know were needed. While you wait 60 to 85 days for a financed buyer to close, you’re also paying for the mortgage, taxes, and insurance. For a deeper look at this process, see our Sell My House Fast for Cash: The Definitive 2026 Homeowner’s Guide.
The Math of a Cash Sale
The cash sale math is much simpler. It looks like this: Offer Price minus $0 Commissions, $0 Repairs, and $0 Closing Costs equals your Net Proceeds. Because professional buyers like LPS Real Estate Group acquire properties as-is, the number we offer is the number you get. You don’t have to worry about 2% or 3% in seller concessions or the risk of a buyer’s financing falling through at the last minute. The best offer is the one that solves your most pressing problem with the most certainty. When you look at the “walk-away” number, a cash offer often results in a nearly identical financial outcome as a traditional sale, but without the months of stress and uncertainty. We focus on providing a clear, manageable path forward so you can move on to your next chapter with peace of mind.
Your Future Starts with a Clear Decision
Selling a home during a stressful season doesn’t have to feel like a gamble. Now that you’ve seen the math behind how cash home buyers determine offer price, you can approach the process with total transparency. Whether it’s calculating the After Repair Value or accounting for holding costs, every number serves a purpose: to provide you with a fast, certain exit from a property that no longer fits your needs. You’ve seen that the “sticker price” of a traditional listing is rarely what you keep, and that creative options exist even when equity is low.
LPS Real Estate Group is here to act as your compassionate expert. We buy houses in any condition, so you don’t have to spend a dime on renovations or cleaning. By choosing a direct sale, you’ll pay no commissions or closing costs, ensuring your net proceeds are protected. For those in complex situations, our creative finance solutions offer a way forward that traditional buyers often overlook. Get your fair, transparent offer from LPS Real Estate Group today. You deserve a partner who values your peace of mind as much as the property itself. Take the next step toward your fresh start today.
Frequently Asked Questions
Do cash home buyers always offer less than market value?
Cash buyers offer a price that reflects the home’s current condition rather than its fully renovated potential. While the number might be lower than a retail listing, you don’t pay commissions or repair costs. This often results in a similar net amount. At LPS Real Estate Group, we also use creative finance solutions to offer more than a standard cash price when your situation requires a higher payout.
How long does it take for a cash buyer to determine an offer price?
Most professional buyers can provide an initial offer within 24 to 48 hours. Because they don’t rely on bank appraisals or long inspection periods, the math is much faster. After a brief walkthrough to verify the home’s condition, the buyer calculates the After Repair Value and renovation budget. This speed is a key part of how cash home buyers determine offer price for sellers who need a certain exit.
Will I have to pay for repairs if I accept a cash offer?
No, you won’t have to pay for any repairs or even clean the property. Cash buyers specialize in as-is property acquisition. They take on the burden of fixing structural issues, updating cosmetics, and hauling away unwanted items. This saves you from spending your own savings or managing contractors. The cost of these future repairs is factored into the initial offer, so the number you see is what you actually keep.
What documents should a serious cash buyer provide to prove they have the funds?
A reputable buyer should provide a Proof of Funds (POF) letter from their bank or a recent bank statement. This document confirms they have the liquid capital available to close the transaction without a mortgage contingency. You should also look for a clear purchase agreement that outlines the terms of the sale. Transparency is vital, so don’t hesitate to ask for these documents early to ensure the buyer is reliable.
Can I negotiate the price with a cash home buyer?
Yes, you can absolutely negotiate the price and terms of a cash offer. A fair buyer will explain the math behind their number, including the estimated renovation costs and market risks. If you have information about recent upgrades or unique neighborhood trends that weren’t considered, you should share them. We view the process as a partnership. Our goal is to find a solution that respects your needs while remaining grounded in market reality.
What is the difference between a cash offer and an iBuyer offer?
iBuyers are large technology companies that typically purchase homes in good condition and charge service fees similar to agent commissions. Direct cash buyers, like LPS Real Estate Group, focus on properties that need work or have complex legal issues. We don’t charge service fees and we take properties as-is. Our approach is more personalized, offering creative finance options that large tech platforms simply don’t provide to homeowners.
How do cash buyers handle properties in probate or foreclosure?
Professional buyers act as experts in complex situations like probate or pending foreclosure. They understand the legal timelines and can work directly with attorneys or lenders to streamline the process. By providing an immediate cash injection, they can stop a foreclosure sale or help heirs settle an estate quickly. This expertise is a significant part of how cash home buyers determine offer price, as they account for the legal hurdles involved.
Are there any hidden fees when selling to a cash buyer?
There should be no hidden fees when selling to a reputable cash buyer. In a traditional sale, you might lose 6% to 10% of your price to commissions and closing costs. With a cash sale, the buyer typically covers the title insurance and escrow fees. You won’t pay for inspections, staging, or marketing. The offer you receive is the amount you’ll see on your settlement statement at the end of the day.