The “responsible” choice of a bank-approved short sale might actually be the most expensive mistake you make in 2026. While it’s often presented as a graceful exit, the reality is a grueling, months-long process that leaves your financial future in the hands of a slow-moving institution. If you’re feeling the weight of an underwater mortgage, you’re likely worried about public foreclosure notices and the long-term destruction of your credit score. It’s a stressful position to be in, and you deserve a path forward that respects your time and your privacy.
When weighing a short sale vs cash offer, it’s vital to understand that the rules have changed. With the expiration of the Mortgage Forgiveness Debt Relief Act earlier this year, forgiven debt is now generally treated as taxable income; making the speed and certainty of a direct sale even more critical. This guide will show you how to protect your equity and avoid a deficiency judgment by choosing strategic alternatives to the bank-led ordeal. You’ll learn how to secure a fast exit in as little as 7 to 14 days, ensuring your borrowing power remains intact for the years ahead.
Key Takeaways
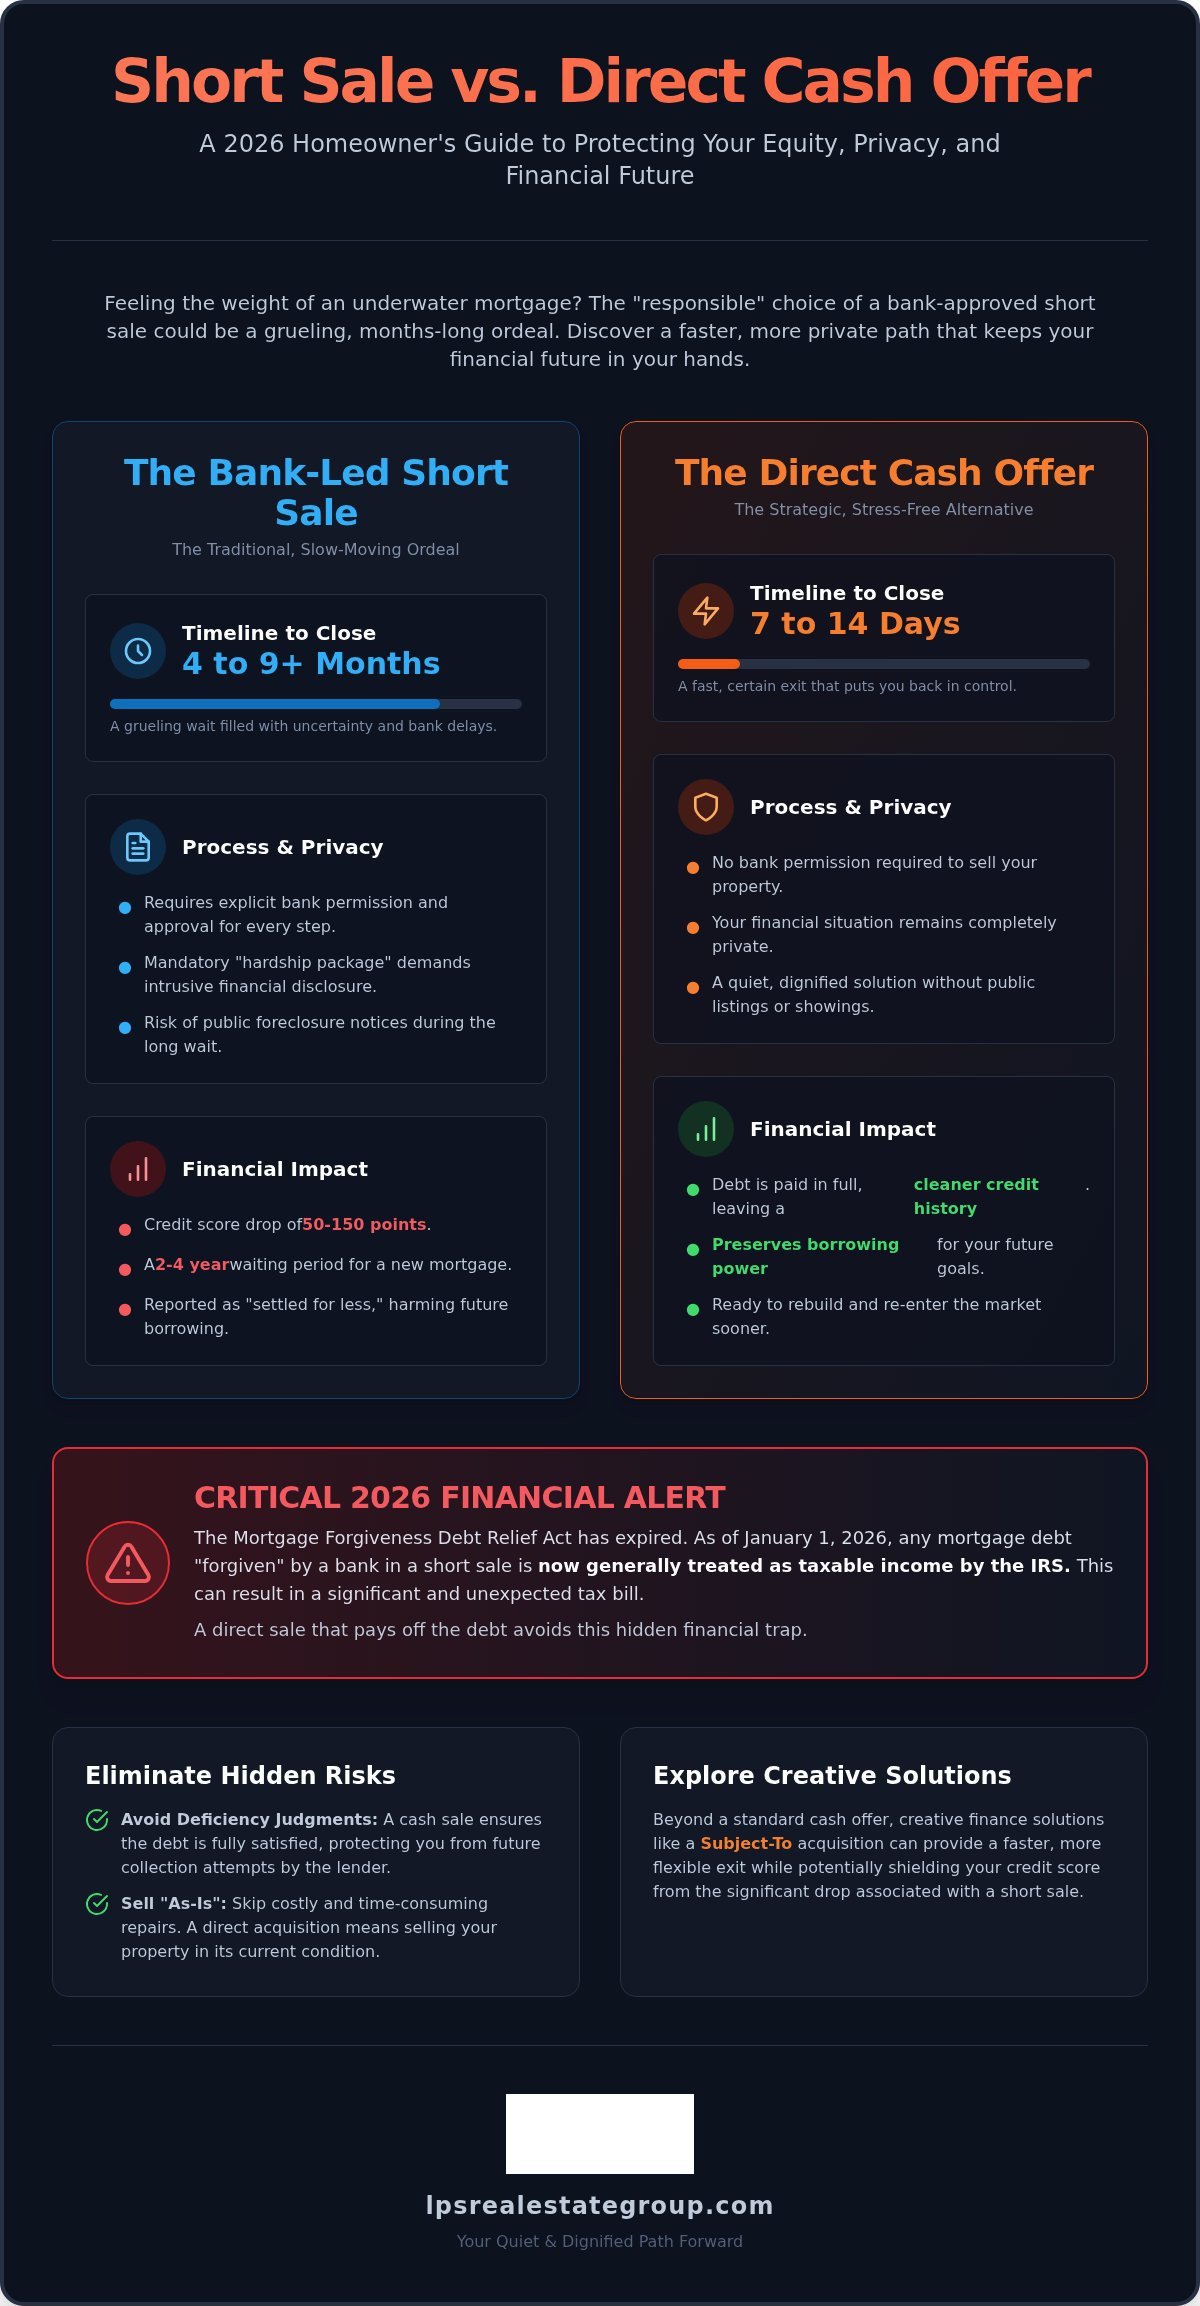
- Understand why the timeline of a short sale vs cash offer differs so drastically, with direct sales closing in as little as 7 to 14 days compared to months of bank negotiations.
- Discover how to bypass the typical 2 to 4 year waiting period required by major lenders after a short sale so you can restore your borrowing power sooner.
- Learn about the updated 2026 tax implications for forgiven mortgage debt and why avoiding a bank-led “hardship package” protects your financial privacy.
- Explore creative finance solutions like Subject-To that allow for a faster exit while potentially shielding your credit score from a significant drop.
- Identify how an as-is property acquisition eliminates the need for costly repairs or public listings, providing a quiet and dignified solution to mortgage stress.
Understanding the Short Sale Process (and Why You Might Want to Avoid It)
A short sale occurs when a homeowner sells their property for less than the remaining mortgage balance. This requires the lender’s explicit permission to “short” the debt and accept a payoff that is less than what’s owed. While it’s often marketed as a graceful exit, the reality is that the bank holds all the cards. They decide if the price is acceptable, which buyers are qualified, and whether you are distressed enough to deserve help. For a comprehensive overview of the short sale process, it’s helpful to look at how these transactions evolved as a tool for lenders to mitigate their own losses rather than a service for the homeowner.
In 2026, the market has shifted significantly. Banks are managing a higher volume of distressed assets, leading to administrative bottlenecks and even slower response times. This makes the comparison between a short sale vs cash offer more critical than ever. Unlike a direct sale, a short sale is a permission-based ordeal that leaves you waiting on a desk in a distant corporate office. It’s vital to remember that a short sale is just one path, it isn’t your only option for a fresh start.
The Reality of Short Sale Approval Timelines
The word “short” in this process is a misnomer. These transactions typically drag on for 4 to 9 months. If you’re facing an active foreclosure date, this timeline is a major risk. Bank bureaucracy is notorious for lost paperwork or sudden requests for updated documents that you’ve already sent. It’s common for a deal to fall through at the eleventh hour because a bank representative didn’t sign off before a deadline. This uncertainty creates immense anxiety for families who need a definitive moving date.
The Requirement for Financial Hardship
To even begin the process, you must prove your “hardship” to the bank. This involves submitting a package that includes a letter explaining your situation, bank statements, tax returns, and pay stubs. It’s a full forensic audit of your personal life that feels incredibly intrusive. The stress of this public financial disclosure is a heavy burden to carry during an already difficult time.
Even after you’ve bared your financial soul, some homeowners are denied. The bank might decide you have too much in your retirement account or that your situation isn’t “dire” enough by their specific metrics. When you look at a short sale vs cash offer, you’ll see that you don’t have to beg for permission to settle your debt and protect your future borrowing power.
The Long-Term Impact of a Short Sale on Your Financial Future
Choosing a short sale vs cash offer isn’t just about today’s move; it’s about where you’ll be in three years. While a short sale is often framed as a way to “save” your credit, it still carries a significant cost. Most homeowners see their credit scores drop by 50 to 150 points. This impact depends on your starting score, but the damage is lasting. It’s a heavy weight to carry when you’re trying to rebuild your life after a financial setback.
The landscape changed significantly on January 1, 2026, with the expiration of the Mortgage Forgiveness Debt Relief Act. Now, any debt the bank forgives in a short sale is generally considered taxable income by the IRS. If a bank “forgives” $50,000, you might face a surprise tax bill as if you earned that money in cash. This shift makes exploring a direct property acquisition a much more attractive path for those who want to avoid unexpected liabilities.
Credit Reporting and Future Borrowing
A short sale is typically coded on your credit report as “settled for less than the full amount.” This label signals to future lenders that you didn’t fulfill your original contract. In 2026, FHA and Fannie Mae guidelines generally require a waiting period of 2 to 4 years before you can qualify for a new mortgage. This delay can feel like a lifetime if you’re ready to start over. In contrast, a direct sale often allows you to pay off the debt in full, leaving a much cleaner history for your future borrowing power.
The Hidden Threat of Deficiency Judgments
Many homeowners don’t realize that a short sale doesn’t always mean the debt is gone. Unless your agreement includes a specific “full satisfaction” or “waiver of deficiency” clause, the bank can still pursue you for the remaining balance. This is known as a deficiency judgment. It’s a legal tool that allows lenders to garnish wages or seize bank accounts years after the house is sold. It’s a “zombie debt” that can haunt your recovery. When you compare a short sale vs cash offer, you’ll find that direct buyers can often structure the purchase to ensure the existing debt is satisfied completely, giving you the true clean break you deserve.
Short Sale vs. Cash Offer: A Strategic Comparison for 2026
Many homeowners feel trapped when they realize their mortgage balance exceeds their home’s value. They often assume a bank-led process is the only way out. However, when you look at a short sale vs cash offer, the differences in control and speed are staggering. A direct purchase gives you the driver’s seat, while a short sale leaves you waiting for a bank’s permission that may never come. By choosing a direct sale, you eliminate the risk of a lender rejecting a traditional buyer’s offer at the last minute, which is a common failure point in bank-managed transactions.
The “As-Is” advantage is another major factor to consider. Traditional buyers usually demand repairs, deep cleaning, and modern staging before they’ll even consider an offer. For a homeowner in financial distress, these costs are often impossible to cover. A direct investment firm buys the property exactly as it stands. You don’t have to fix the leaky roof or worry about the outdated kitchen. This saves you thousands of dollars and weeks of stressful renovation work during an already difficult time.
Speed and Foreclosure Prevention
A traditional sale comes with heavy baggage: 6% in commissions and roughly 2% in closing costs. In a short sale vs cash offer scenario, these fees can be the difference between settling the debt and staying underwater. Direct investment firms typically charge zero commissions and cover all closing costs. Saving that 8% of the home’s value can sometimes bridge the gap between your mortgage balance and the sale price, making a full payoff possible without the bank’s interference. If you’re looking for a way to move forward, it’s worth researching companies that buy houses for cash to see how they can simplify your exit strategy.
Proven Alternatives: How to Bypass the Bank’s Bureaucracy
The bank often makes it feel like you have only two choices: pay up or face foreclosure. This isn’t true. By the time you are comparing a short sale vs cash offer, you have already taken a brave step toward a solution. Acting while you still have even a small amount of equity or a few weeks before an auction date opens doors to strategies that banks rarely mention. These alternatives prioritize your financial recovery and your privacy rather than the lender’s bottom line.
The Power of Creative Finance
One of the most effective ways to protect your credit is through a “Subject-To” real estate offer. In this scenario, a professional buyer takes over your monthly mortgage payments while the existing loan stays in your name. This is a powerful tool because it stops the immediate threat of foreclosure and ensures that future payments are made on time. Over several months, these consistent payments can actually help rehabilitate your credit score, which is a far better outcome than the damage caused by a traditional settlement. If you want to explore these options further, read our guide on creative real estate exit strategies to see how they provide certainty in today’s market.
Working with a Direct Property Acquisition Firm
A direct cash sale is often the cleanest way to liquidate an asset and satisfy a debt quickly. When you work with an investment firm, you bypass the intrusive “hardship package” requirements of a bank. However, it’s vital to vet your buyer. Ensure they have a proven track record of closing and don’t rely on traditional bank financing themselves, which could fail at the last minute.
The primary benefit of this path is the ability to sell house as is. Many distressed properties wouldn’t pass a formal bank inspection required for a standard mortgage. A direct buyer accepts the property with all its flaws, whether it needs minor cleaning or major structural work. This removes the financial burden of repairs from your shoulders entirely. When comparing a short sale vs cash offer, remember that a cash buyer offers a level of finality that a bank-managed process simply cannot match.
If you are ready for a transparent, no-pressure conversation about your specific situation, contact LPS Real Estate Group today to see which alternative fits your goals.
As a last resort, some homeowners consider a Deed in Lieu of Foreclosure. This involves voluntarily handing the property deed back to the lender. While it stops a foreclosure, it still leaves a significant mark on your credit and often requires the property to be in broom-clean condition. Compared to a direct sale, it offers very little control and no opportunity to walk away with any remaining equity. Choosing a proactive strategy while you still have time is always the more advantageous path.
Partnering with LPS Real Estate Group for a Stress-Free Exit
LPS Real Estate Group provides a compassionate alternative to the cold, bureaucratic bank process. We don’t view your home as just another file on a desk. Instead, we see a family looking for a fresh start and a way to protect their future. Our commitment to transparency means you’ll never face hidden fees or high-pressure sales tactics. We offer clear solutions that prioritize your peace of mind over bank profits. We take the time to listen to your specific needs before suggesting a path forward.
Dealing with title issues or aggressive lender communication can be overwhelming. We handle these complexities for you. Our team takes over the administrative burden, ensuring that every detail is handled with integrity and professional care. When you compare a short sale vs cash offer, remember that we offer a streamlined path that bypasses the intrusive “hardship packages” required by traditional institutions. We manage the heavy lifting so you don’t have to.
Our 3-step process is designed for simplicity and speed:
- Reach Out: Share your situation with us in a private, one-on-one consultation.
- Property Evaluation: We review your property’s condition exactly as it stands today.
- Fair Offer: Receive a no-obligation offer that allows you to close on your timeline, typically within 7 to 14 days.
A Compassionate Approach to Foreclosure Prevention
We treat every homeowner like a partner, not a transaction. This “quiet confidence” approach allows us to provide stability during high-stress situations. We believe that honesty is the best way to build a bond with our clients. If you’re currently facing a deadline, our pre-foreclosure guide offers additional insights into how you can protect your equity with dignity. We focus on doing the right thing for your unique circumstances.
Your Next Steps Toward Financial Freedom
A consultation is the first step to explore all available exit strategies. You can receive a fair offer without the stress of a public listing or the uncertainty of a short sale vs cash offer negotiation with a bank. This is about closing a difficult chapter with certainty. By avoiding the bank’s bureaucracy, you protect your future borrowing power and gain the freedom to move forward. We’re here to help you find a solution that feels fair and manageable, allowing you to focus on what comes next.
Take Control of Your Financial Recovery
Deciding how to handle an underwater mortgage is a significant step toward reclaiming your peace of mind. The choice between a short sale vs cash offer often comes down to who you want in control of your timeline. A bank-led process can take months and expose your private finances; however, a direct sale provides a certain exit in as little as 7 to 14 days. By choosing a proactive path, you avoid the long waiting periods and credit damage that typically follow a standard bank settlement.
To gain a deeper perspective on how to navigate the traditional real estate landscape and avoid common pitfalls, you can check out Robert Caicedo Real Estate for expert advice on mastering the current market.
Similarly, homeowners in Nevada can consult with Las Vegas residential real estate agents to get a localized perspective on their property’s value and the most effective ways to settle mortgage debt in the current climate.
LPS Real Estate Group consists of national experts in foreclosure prevention and creative finance. We’re dedicated to providing fair solutions with zero commissions, zero closing costs, and zero repairs required. Our A+ rated professional property acquisition team handles every detail with the integrity and care you deserve. You don’t have to navigate this stressful chapter alone.
Request Your Fair Cash Offer and Avoid a Short Sale Today. We’re ready to listen to your situation and help you move forward with the confidence of a clean break and a bright financial future.
Frequently Asked Questions
Is a short sale worse than a foreclosure on my credit report?
Foreclosure is generally more damaging to your financial future than a short sale. A foreclosure can stay on your credit report for up to seven years and often causes a 100 to 200 point drop in your score. In contrast, a short sale typically results in a 50 to 150 point impact. Choosing a short sale also reduces the waiting period for a new mortgage to roughly two to four years, whereas foreclosure usually requires a seven-year wait.
Can I avoid a short sale if I am already in pre-foreclosure?
You can absolutely avoid a short sale during the pre-foreclosure phase. This period is your window of opportunity to take control before the bank completes the legal process. By securing a direct sale, you can pay off your debt and stop the public auction. This path is often faster and more private than waiting for a lender to approve a traditional short sale application, which can drag on for months while your credit suffers.
How long does it take to get a cash offer from LPS Real Estate Group?
You can receive an initial offer from our team within 24 to 48 hours of your first consultation. Once you accept the offer, the entire process can close in as little as 7 to 14 days. This speed is specifically designed to help homeowners who are facing urgent deadlines, such as a scheduled foreclosure auction. We prioritize a fast and certain timeline so you can resolve your mortgage stress quickly and move forward.
Do I have to pay any fees or commissions when selling to a direct buyer?
You don’t have to pay any commissions or closing costs when selling to a direct property acquisition firm like ours. Traditional sales often involve an 8% deduction from your proceeds for agent fees and title costs. We eliminate these expenses entirely. Because we buy the property as-is, you also save money by avoiding repairs, deep cleaning, or professional staging. This transparency ensures you know exactly what you will walk away with at closing.
What happens to my mortgage if I sell to a cash buyer for less than I owe?
When weighing a short sale vs cash offer, the goal is to satisfy the debt completely. If the cash offer is less than the balance, we can explore creative finance solutions like a Subject-To purchase. This allows us to take over your monthly payments, keeping the loan in place while protecting your credit history. It’s a strategic way to handle an underwater mortgage without the bank’s grueling approval process or intrusive financial audits.
Can I stay in my home after the sale is complete?
Most direct property acquisitions involve the seller moving out at the time of closing. However, we understand that every situation is unique. In certain cases, we can discuss a flexible move-out date or a short-term lease-back agreement. This allows you to secure your funds and resolve your debt while giving you the necessary time to transition into your next living arrangement with dignity and peace of mind.
What is the difference between a short sale and a direct property acquisition?
The main difference is control. A short sale requires the lender’s permission, which can take four to nine months and involves a forensic audit of your personal finances. A direct property acquisition is a private agreement between you and the buyer. It bypasses the bank’s bureaucracy, closes in a fraction of the time, and doesn’t require you to prove financial hardship to a distant corporate office just to settle your own debt.
Will a cash buyer purchase my home if it needs significant repairs?
We purchase homes in any condition. You don’t need to fix a leaky roof, update the kitchen, or even clear out unwanted belongings. We specialize in as-is property acquisition, which means we take on the burden of all future repairs and cleaning. This is particularly helpful for distressed properties that might not qualify for a traditional bank loan due to inspection failures, structural issues, or outdated systems that a typical buyer wouldn’t accept.