Did you know that nearly 32% of home sales in 2026 are now all-cash transactions? As mortgage rates stay elevated near 7%, many homeowners are discovering that the traditional path of listing, cleaning, and waiting is no longer the most reliable way to move forward. If you’re feeling exhausted by endless showings or anxious about costly repairs demanded by picky buyers, you aren’t alone. You might be asking yourself, how does a cash offer on a house work, and is it a safe, viable option for your family’s specific situation?
We understand that selling a home is often about more than just a transaction; it’s about finding relief and a clear path through a stressful time. You can bypass the traditional market entirely and secure a certain, fast cash offer without fixing a single leaky faucet or paying agent fees. This guide provides a clear checklist to help you secure a firm offer within 24 hours and close on a date of your own choosing. We’ll walk you through the 2026 process, including how to handle new transparency regulations and why an as-is sale might be the most compassionate choice for your future.
Key Takeaways
- Understand the mechanics of how does a cash offer on a house work to bypass lender appraisals and avoid the “mortgage contingency trap” that frequently delays traditional sales.
- Learn how to secure a firm, no-obligation offer within 24 hours so you can sell your property in its current condition without spending money on repairs or cleaning.
- Follow our 7-day closing checklist to achieve immediate liquidity and move on your own timeline, regardless of the property’s condition or complexity.
- Discover how creative finance and direct acquisitions can resolve difficult situations like foreclosure or probate while maintaining your equity and peace of mind.
- See why choosing a transparent, human-centric partner means you won’t have to worry about hidden fees, agent commissions, or last-minute price drops.
Why Traditional Listings Fail the “Immediate” Test in 2026
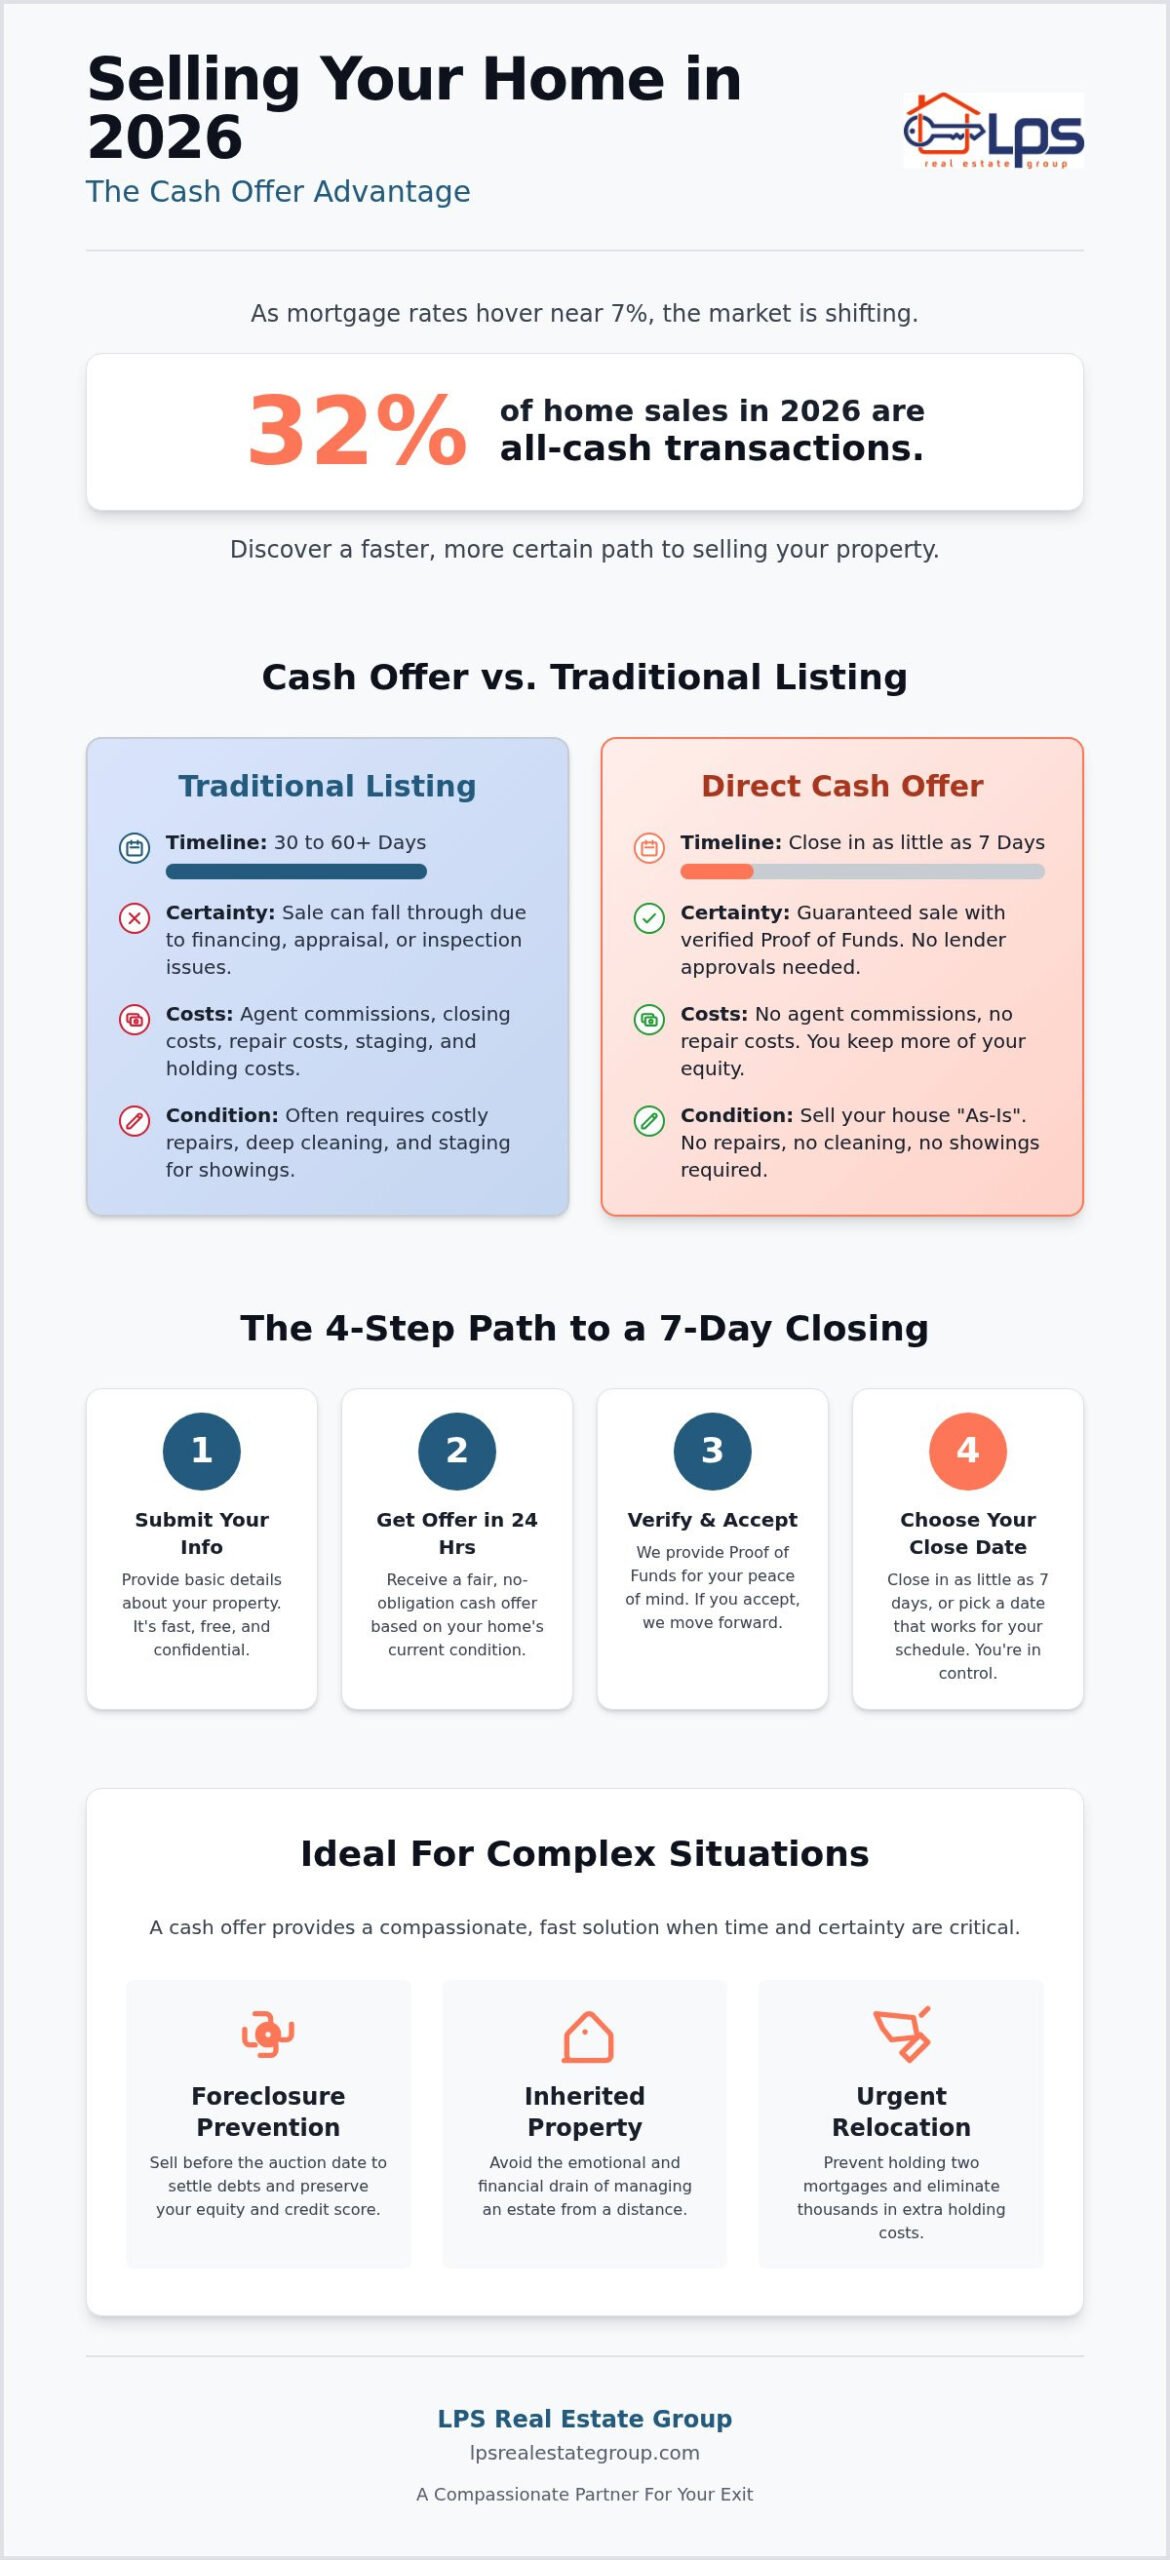
Traditional listings often promise the highest possible price, but they rarely mention the high cost of waiting. In 2026, the average traditional mortgage-backed closing takes 30 to 60 days. This doesn’t even include the weeks spent deep-cleaning, staging, and hosting endless showings. For many, this timeline is a luxury they simply can’t afford. You might be wondering, how does a cash offer on a house work compared to this slow-moving machine? It starts by removing the most common obstacles that cause sales to collapse at the finish line.
The biggest deal-killer today is the “mortgage contingency” trap. With 30-year fixed rates hovering between 6.71% and 6.99%, lenders are more cautious than ever. A buyer might love your home, but if their financing falls through at the last minute, you’re back at square one. Your home now carries the “days on market” stigma, which often leads to lower future offers. This delay is often compounded by appraisal gaps, where a bank refuses to lend the full amount, and inspection demands that force you to make expensive repairs before the sale can even proceed.
The Reality of the 2026 Housing Market
The current market has shifted toward a need for certainty. While nearly 32% of home sales in 2026 are now all-cash, many sellers still find themselves stuck in the traditional cycle. What is a cash offer? In simple terms, it’s a direct purchase that removes the middleman, the bank. By choosing an “as-is” acquisition, you avoid the stress of fixing structural issues or clearing out a hoarder house. You trade the gamble of a high listing price for the stability of a guaranteed exit. This is why “as-is” buyers have become the preferred route for properties that need more than just a fresh coat of paint.
When Speed Becomes a Necessity, Not a Luxury
For those facing a foreclosure auction or a probate deadline, time is a finite resource. A 60-day wait isn’t just inconvenient; it’s a financial risk that could lead to a lost inheritance or a ruined credit score. We focus on providing a clear, manageable path forward for these complex situations.
- Foreclosure Prevention: Selling before the auction date allows you to settle debts and preserve your equity.
- Inherited Property: Managing an estate from a distance is emotionally draining. A fast break allows the family to move forward without the burden of maintenance.
- Relocation: Holding two mortgages while waiting for a traditional buyer to get approved can cost thousands in holding costs.
We believe homeowners deserve a partner who respects their timeline. By understanding how does a cash offer on a house work, you can regain control and choose a closing date that fits your life, not the bank’s schedule.
The Mechanics of an Immediate Cash Offer
An immediate cash offer is a direct purchase agreement where the buyer uses liquid funds rather than a bank mortgage. This structure allows both parties to skip the time-consuming lender appraisal process entirely. For a seller, the most critical step in this process is verifying the buyer’s Proof of Funds (POF). Seeing a current bank statement provides the certainty that the transaction won’t stall. By removing the traditional middleman, you also eliminate the real estate commissions and various hidden transaction fees that typically eat into your equity.
How Cash Buyers Determine Your Offer
Professional buyers use a specific formula to ensure the offer is fair and sustainable. They start with the After Repair Value (ARV), which is what the home could sell for if it were fully renovated according to 2026 standards. From there, they subtract the estimated costs for repairs, holding costs, and a small margin for risk. This “As-Is” approach means the offer is based on the property’s current condition, not its future potential. Understanding how to make a cash offer helps sellers see that while the gross number might be lower than a retail listing, it’s often the exact “net” amount you actually take home. An Immediate Cash Offer is a tool for financial freedom and speed, providing a clean break from the burdens of property ownership. If you’re looking for this type of clarity, you can request a transparent valuation to see how the numbers work for your specific home.
The Role of Title and Escrow in Fast Closings
Speed doesn’t mean cutting corners; it means working with experts who know how to navigate legal hurdles. Title companies can expedite searches for cash deals because they don’t have to wait for lender red tape or secondary approvals. If your property has liens, judgments, or complex probate issues, a professional buyer often handles this paperwork for you. They work directly with the title company to clear these clouds from the title before closing. The final step is often the most convenient: the “Mobile Notary” experience. Instead of driving to a law office, you can sign the final documents at your kitchen table on your own schedule. This focus on your comfort is a core part of how does a cash offer on a house work to provide relief during difficult transitions. By removing the need for bank intervention, the entire process moves at the speed of your needs rather than the speed of a lender’s bureaucracy.
Pure Cash vs. Creative Financing: Maximizing Your Speed and Equity
Choosing between a pure cash buyout and a creative finance solution depends entirely on your financial goals and the amount of equity in your home. A pure cash offer is the fastest route for homeowners with high equity or those dealing with distressed properties that need a quick resolution. It answers the fundamental question of how does a cash offer on a house work by providing a direct, liquid payment that closes in as little as 7 to 14 days. This “cash and walk” option is the gold standard for simplicity, especially when dealing with inherited estates or houses requiring significant repairs.
However, not every situation fits a standard buyout. If you owe more than your home is currently worth or have very little equity, a traditional cash offer might not cover your existing mortgage. In these cases, creative finance solutions offer a manageable path forward. One common method is a “Subject-To” deal, where the buyer takes over your existing mortgage payments. This strategy can stop a foreclosure process instantly, as it brings the loan current and removes the monthly debt burden from your shoulders without requiring a bank’s lengthy approval process.
Choosing the Strategy That Fits Your Goal
Deciding which path to take requires a clear look at your mortgage balance and your need for speed. If you’re “underwater” on your loan, creative financing can help you exit the property without having to bring cash to the closing table. For a more detailed breakdown of these options, you can explore our guide on Creative Real Estate Exit Strategies. This resource helps homeowners understand how to find certainty even in complex financial landscapes.
The “Certainty” Factor in Creative Offers
A common misconception is that creative finance is less secure than a cash sale. In reality, these transactions are just as legitimate and use the same legal protections, including professional title companies and escrow services. In some cases, a strategy like a Seller Carryback, where you act as the lender, can actually secure a higher total purchase price than a standard cash buyout. This approach provides you with steady monthly income while the buyer handles all property maintenance and taxes. We believe in providing full transparency so you can choose the strategy that offers the most relief and the highest value for your specific circumstances.
The 7-Day Closing Checklist: Your Path to Immediate Liquidity
If you’ve spent time researching how does a cash offer on a house work, you’ve likely realized it’s about stripping away the friction of the traditional market. While a bank-funded sale often feels like a series of hurdles, a direct purchase is a streamlined sequence designed for speed. This checklist outlines the exact path from your initial inquiry to receiving funds in your account, often in as little as 7 days.
- Step 1: Submit your property details for a preliminary desktop analysis and valuation.
- Step 2: Receive and review your no-obligation offer within 24 hours of submission.
- Step 3: Schedule a single, brief walkthrough to verify the property’s condition.
- Step 4: Sign the simple purchase agreement and select your specific closing date.
- Step 5: Hand over the title work to the buyer’s professional team for expedited processing.
This methodical approach ensures that you aren’t left wondering about the status of your sale. By removing the need for mortgage approvals or secondary inspections, we move directly from a handshake to a finalized agreement.
Preparing for the Walkthrough
One of the greatest points of relief for homeowners is realizing they don’t need to clean, paint, or repair anything before the buyer visits. In a traditional sale, you might spend thousands on “curb appeal” just to get people through the door. In an as-is cash sale, the buyer is actually looking for the bones of the house. They focus on major systems like the HVAC, roof, and foundation. If you’re dealing with an inherited property or a hoarder situation, our “Take What You Want, Leave the Rest” policy means you can walk away with your personal treasures and let us handle the heavy lifting and clean-out process.
Finalizing the Paperwork
To keep the process moving toward a 7-day closing, it’s helpful to have a few basic documents ready. You’ll generally need a valid ID, your most recent mortgage statement, and any relevant HOA information. Because there is no lender involved, the title company can work much faster. On the day of closing, the funds are sent via wire transfer or certified check directly to your account. For more preparation tips on moving from “listed” to “sold,” you can read our pillar guide on Sell My House Fast for Cash. If you’re ready to see your own numbers, you can get your cash offer started today and see how simple the process can be.
LPS Real Estate Group: A Compassionate Partner for Your Exit
LPS Real Estate Group isn’t just another corporate entity looking for a transaction. We operate as a compassionate expert for homeowners who need a clear, reliable exit strategy. While many large competitors rely on automated systems and high-pressure tactics, we prioritize a quiet, confident approach. We start by listening to your unique situation. This allows us to understand the hurdles you’re facing, whether it’s a looming foreclosure or a complex probate case. Our “Transparency First” promise means you won’t encounter hidden fees, agent commissions, or last-minute price drops. When you ask, how does a cash offer on a house work with us, the answer is simple: it works through partnership and honesty.
The LPS difference lies in our ability to solve the technical issues that often stop other buyers in their tracks. We frequently resolve complex title clouds and lien issues that would otherwise derail a sale. This expertise provides a level of certainty that mortgage-backed buyers simply cannot offer in the 2026 market. We don’t just provide a checkbook; we provide a way out of a stressful situation. For those seeking professional real estate guidance in Southern California, you can visit Adria Chamberlain | Keller Williams High Desert to connect with a dedicated expert in the High Desert and Inland Empire communities.
Dealing with the loss of a loved one or a financial crisis is already heavy enough. We work closely with heirs and executors to help them move through the probate process with ease. We don’t just buy the property; we help manage the logistical weight of the estate. For those facing foreclosure, we provide strategies to stop the auction immediately. This protects your financial future and prevents a long-term hit to your credit score. Every home has a story and deserves a fair exit strategy. We respect that story by offering solutions that prioritize your peace of mind over our bottom line. While we specialize in direct acquisitions for complex situations, those with premium coastal homes may also wish to discover DeFeo Luxury Properties for specialized representation in the Tampa and Sarasota luxury markets.
Get Started with Certainty Today
We believe that the best decisions are made without pressure. Our no-pressure consultation is designed to help us understand your goals first. There’s no obligation to accept an offer, and we’ll never use aggressive sales tactics to push you forward. Requesting your offer comes with zero risk or cost to you. By understanding how does a cash offer on a house work in your specific context, you can move forward with the confidence that you’ve chosen the right path for your family. Ready for a fair cash offer? Contact LPS Real Estate Group today.
Take Control of Your Property Exit Today
Navigating the 2026 housing market doesn’t have to be a source of constant anxiety. By understanding how does a cash offer on a house work, you’ve taken the first step toward reclaiming your time and peace of mind. You now have the tools to bypass the uncertainty of lender approvals and the exhaustion of endless showings. Whether you choose a direct cash buyout or a creative finance solution, the goal is the same: providing you with a certain, manageable path forward.
At LPS Real Estate Group, we specialize in providing relief for homeowners facing complex situations. Our expertise in probate and foreclosure prevention ensures that even the most difficult title issues are handled with care and integrity. We offer an as-is purchase guarantee with absolutely no commissions or hidden fees, allowing you to keep more of your equity. It’s time to move past the stress of repairs and cleaning and start your next chapter on your own terms.
Get Your Immediate, No-Obligation Cash Offer from LPS Real Estate Group
You’ve done the hard work of researching your options; now let us handle the heavy lifting. We’re here to listen and help you find the best possible outcome for your unique situation.
Frequently Asked Questions
Is an immediate cash offer legitimate?
Yes, cash offers are entirely legitimate and follow the same legal transfer laws as traditional residential sales. We use professional title companies and escrow services to ensure every transaction is documented, safe, and legally binding. A reputable buyer will always provide a Proof of Funds up front to verify their ability to close. This transparency protects you and ensures that the funds are liquid and ready for a certain closing.
How much below market value is a cash offer?
Cash offers are often lower than retail listings because they account for speed, certainty, and the total lack of repairs. While industry data from 2026 suggests sellers might accept a discount of 9% to 11% compared to financed offers, you should focus on your “net” gain. When you subtract the 6% agent commission and repair costs, the difference is often minimal. This is a core part of how does a cash offer on a house work to provide immediate liquidity.
Can I sell my house for cash if I am behind on mortgage payments?
You can certainly sell your home even if you are behind on payments or facing an active foreclosure. We specialize in foreclosure prevention purchases that can stop an auction and protect your credit score. By purchasing the property before the bank takes title, we help you settle the debt and potentially walk away with your remaining equity intact. It’s a compassionate way to find a fresh start during a difficult financial time.
What happens if my house needs major repairs like a new roof or foundation?
We purchase properties in any condition, including those with major structural issues like foundation cracks, mold, or failing roofs. You don’t need to spend a single dollar on renovations or even basic cleaning. Our as-is acquisition model means we take on the risk and the repair costs after the sale is complete. This allows you to exit a burdensome property without the stress of managing contractors or paying for expensive materials.
Do I need a real estate agent to sell my house for cash?
You don’t need a real estate agent to sell your house for cash. By selling directly to LPS Real Estate Group, you bypass the need for an MLS listing and the traditional commission fees. This direct relationship simplifies the communication and ensures that you are working with the decision-maker throughout the entire process. It’s a more personal, transparent way to handle a property transfer without the interference of third-party fees.
How fast can I actually get the money in my bank account?
Most cash transactions can be finalized in as little as 7 to 14 days. This timeline is significantly faster than the 30 to 60 days required for mortgage-backed buyers in the 2026 market. The actual speed depends on how quickly the title search is completed and your own preferred closing date. Once the documents are signed at the title company, the funds are typically wired to your bank account on the same day.
Are there any closing costs when selling to a cash buyer?
When you sell to a professional cash buyer like us, we typically cover all the standard closing costs. This includes title insurance, escrow fees, and recording fees that usually fall on the seller in a traditional transaction. Our “Transparency First” promise ensures that the offer you see is the amount you actually receive. You won’t have to worry about hidden deductions or last-minute financial surprises at the final closing table.
What if the house is currently occupied by tenants or squatters?
We are experienced in handling properties that are currently occupied by tenants or even squatters. You don’t need to go through the stressful eviction process or handle difficult confrontations before selling to us. We take over the property with the existing occupants and handle all legal and logistical matters from that point forward. This is another way how does a cash offer on a house work to solve complex problems for the homeowner.