Selling the home may solve one problem while creating another: it can turn a home into cash that affects Medicaid eligibility. Selling a house to pay for long term care can make sense when the proceeds are needed for care and keeping the property is no longer practical, but the right choice depends on the family’s care plans, finances, and benefit eligibility. Medicaid’s look-back period is generally the 60 months immediately before an application, so the timing and handling of assets matter.
It’s understandable to want a clear way to fund care without rushing a decision about a home that carries financial and personal meaning. This guide explains how to weigh a sale, when timing may matter, and who can legally authorize it. It also covers financial, tax, elder-law, and estate-planning questions, along with alternatives to consider if selling may not be the best fit.
As you compare options, consider both the immediate need for care and the longer-term effects on the homeowner and family. The sections ahead offer a practical way to work through those decisions and approach the next step with greater clarity.
Key Takeaways
- Compare the care funding a sale could provide with the ongoing costs and responsibilities of keeping the home.
- Consider the timing of a sale alongside tax rules and the parent’s care needs, rather than treating it as a purely financial decision.
- Confirm who has legal authority to sell and whether the homeowner can make the decision independently.
- Bring financial, elder law, and estate-planning considerations into the decision before choosing how to use the proceeds.
1. Should you sell a house to pay for long-term care?
Selling a house to pay for long term care can make sense when care expenses exceed available income and savings. Proceeds may cover assisted living costs or supplement pensions and long-term care insurance. Selling can also end property tax and maintenance responsibilities, although the home may hold deep emotional value for your parent.
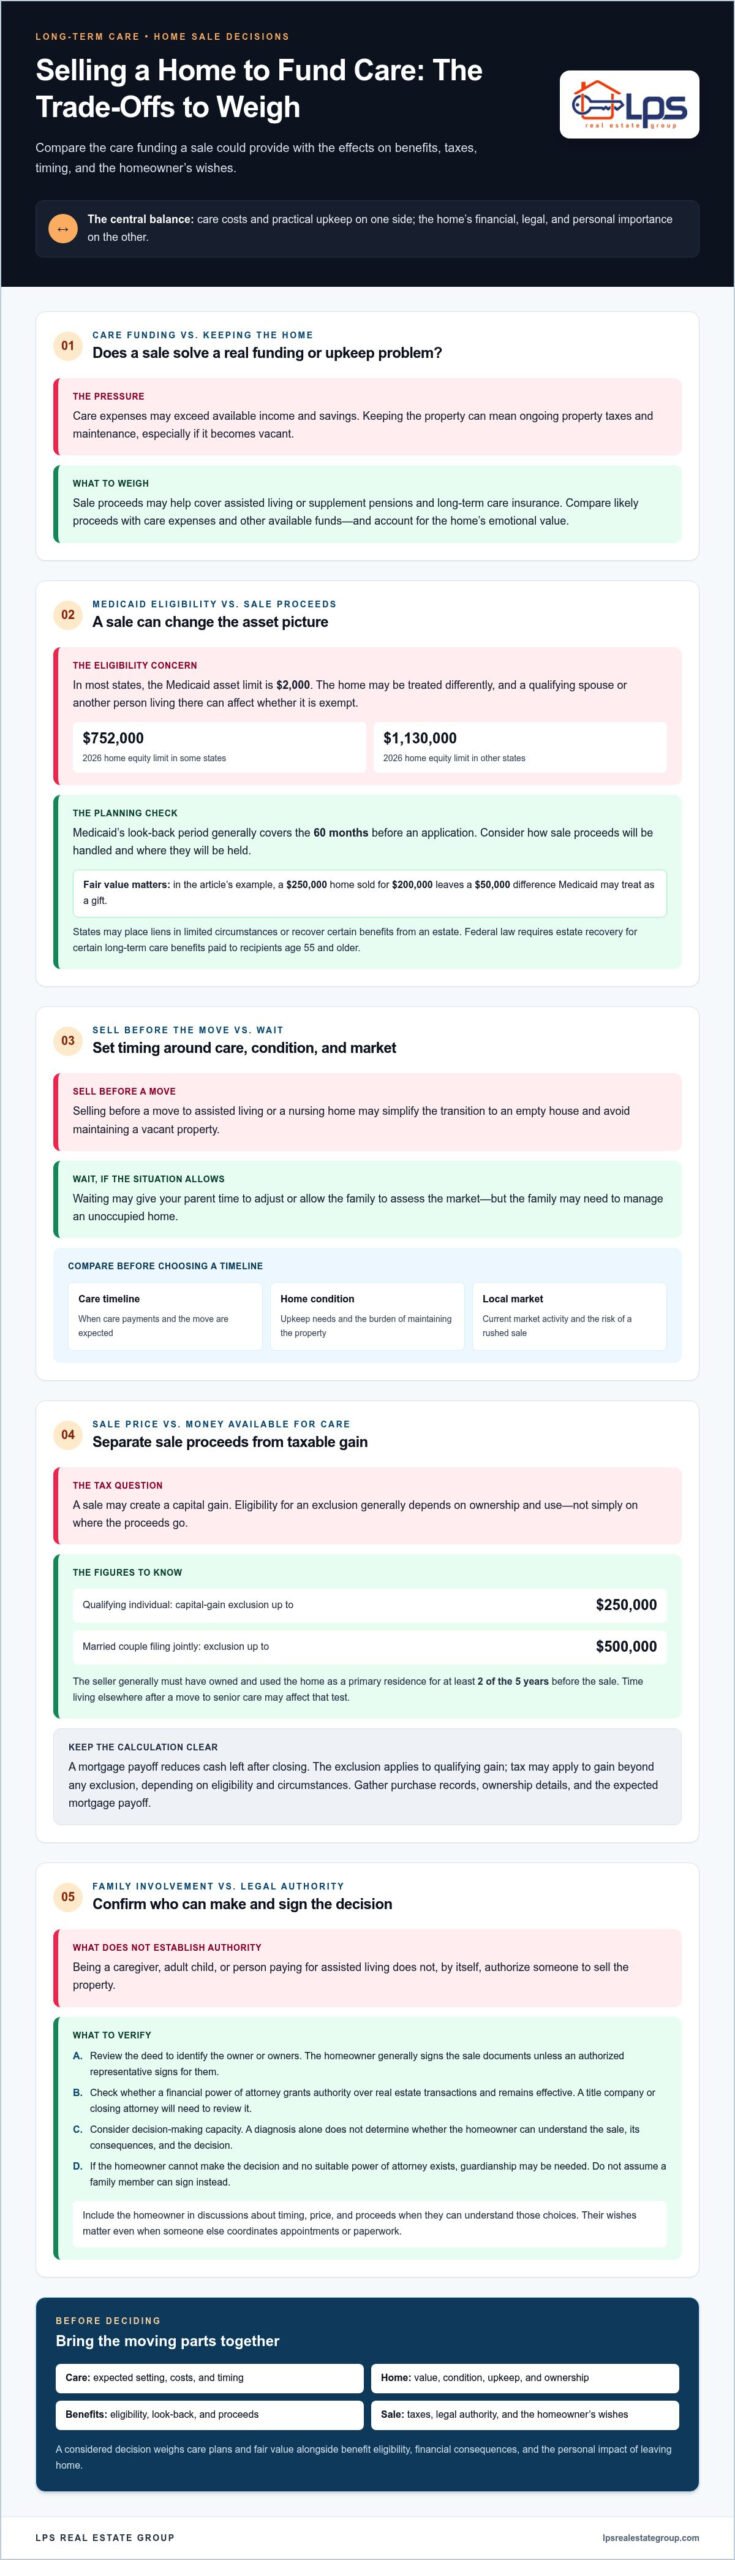
Medicaid eligibility adds another consideration. In most states, the asset limit is $2,000, while 2026 home equity limits are generally $752,000 or $1,130,000, depending on the state. A qualifying spouse or other person living in the home can affect whether it is exempt. Medicaid’s look-back period generally covers the 60 months before an application. Selling below fair market value may create a problem: a $250,000 home sold for $200,000 leaves a $50,000 difference Medicaid may treat as a gift. States may place liens in limited circumstances or recover certain benefits from the estate after a recipient dies. Federal law requires estate recovery for certain long-term care benefits paid to recipients age 55 and older.
To plan a sale alongside care arrangements, first identify the expected care setting and funding needs. Review ownership, estimate the home’s value, and compare likely proceeds with care expenses and other available funds. If you’re selling a house to pay for long term care, consider how the proceeds could affect Medicaid eligibility and where the money will be held.
Timing depends on the move and the property’s condition. Selling before a move may simplify the transition and avoid maintaining a vacant home. Waiting may give your parent time to adjust or let the family assess the market. Compare local market conditions and upkeep needs, then choose a timeline that balances care funding with a considered sale.
Moving quickly can involve trade-offs: a rushed sale may bring in less, while selling below fair market value can affect Medicaid eligibility. Sale-related taxes may also apply, and keeping the home means ongoing taxes and maintenance. Weigh these financial considerations against the emotional impact of leaving the home. Selling a house to pay for long term care works best as a considered decision that accounts for fair value, care plans, and benefit eligibility.
2. When Is the Right Time to Sell Your Parent’s Home to Pay for Senior Care?
Timing a sale means balancing the senior’s move, care funding, and possible tax consequences. Selling before a move to assisted living or a nursing home can simplify the transition to an empty house. Waiting may give your parent time to adjust, but the family may need to manage an unoccupied property. Consider the care timeline alongside the home’s condition and local market activity.
For tax purposes, a home sale may create a capital gain, but an exclusion can reduce the taxable amount. According to the Internal Revenue Service, a qualifying individual selling a home in the United States may exclude up to $250,000 of capital gain. A married couple filing jointly may qualify to exclude up to $500,000 of capital gain from a home sale in the United States, according to the Internal Revenue Service.
Eligibility generally depends on ownership and use, not simply on where the proceeds go. According to the Internal Revenue Service, the seller generally must have owned and used the property as their primary residence for at least two of the five years before the sale. If your parent moved to senior care, consider how time living elsewhere affects that test.
When considering how a home sale is taxed while funding long-term care, separate the gain from the cash available after closing. A mortgage payoff reduces the proceeds left for care, while the capital-gains exclusion applies to qualifying gain. If the sale price exceeds the home’s original purchase price, tax may apply to gain beyond any exclusion, depending on eligibility and circumstances.
Before setting a closing date, gather purchase records, ownership details, and the expected mortgage payoff. Compare the likely net proceeds with the timing of care payments, then weigh those needs against current local market conditions. If a direct sale is under consideration, explore a direct home sale as one possible route, while keeping tax eligibility and care timing in view.
3. Who needs legal authority to sell the home?
The homeowner generally signs the real estate sale documents, or an authorized representative signs on their behalf. Review the deed to identify the owner or owners, then locate any financial power of attorney. Being a caregiver, adult child, or person paying for assisted living does not, by itself, establish authority to sell the property.
A financial power of attorney can authorize a designated person to manage financial matters, including selling property. The document’s wording matters: check whether it grants authority over real estate transactions and remains effective. A title company or closing attorney will need to review the document before relying on it. The agent should act in the homeowner’s interests and handle sale proceeds as the document requires.
Decision-making capacity also matters. A person with dementia may sell a house only if they have the mental capacity to do so. A diagnosis alone doesn’t determine whether someone can understand the sale, its consequences, and the decision being made. If your parent can understand those points, include them in discussions about timing, price, and where the proceeds will go. Their wishes matter even when a caregiver coordinates appointments or paperwork.
If the homeowner can’t make the decision and no suitable power of attorney exists, a family member shouldn’t assume they can sign instead. Guardianship may be needed to obtain legal authority for financial decisions, including a home sale. The governing court order sets the scope of that authority, so review it before taking steps to sell. This can affect the timing of a move to assisted living and access to the home’s value.
Before listing the home or accepting an offer, follow this sequence: confirm ownership, read the power of attorney or court order, and identify who must sign. Share the relevant documents with the closing attorney or title company, and resolve questions about authority before setting a closing date. Clear roles help prevent a sale from stalling after the family has planned care around its proceeds.
4. Financial, elder law, and estate-planning advice
A home sale can affect income, benefits, taxes, and inheritance at once. Before deciding, ask a financial advisor to compare expected sale proceeds with monthly senior care expenses, pensions, savings, and insurance. Include the mortgage payoff and ongoing home costs in that estimate. Medicare does not cover long-term services and supports, so families need to identify other funding sources.
An elder-law attorney can explain how a sale may affect Medicaid eligibility, asset limits, and estate recovery. A primary residence may be excluded from Medicaid’s asset limit when qualifying conditions apply, such as a spouse living there or the applicant intending to return home. Selling changes the asset from home equity to cash, which may be treated differently. Ask how the state treats the proceeds and what records the family should keep.
Veterans benefits require a separate review. The U.S. Department of Veterans Affairs has a three-year lookback period for asset transfers; gifting assets or selling below fair market value can lead to a period of ineligibility. A financial advisor can also compare selling with alternatives, such as renting the home or using a reverse mortgage. A reverse mortgage may provide cash while a senior remains in the home, but repayment often becomes due when the homeowner no longer lives there.
Estate planning adds another layer. An estate planner can review ownership, trusts, inheritance goals, and how sale proceeds should be managed. For example, jointly owned property or a home held in trust can affect tax treatment and who receives the proceeds. Bring the deed, mortgage information, benefit details, and existing estate documents to the discussion. Ask each advisor to explain how their recommendations fit together before signing documents or transferring assets.
Use the advice to compare choices, not to delay urgent care arrangements. If a sale fits the family’s plan, explore home sale options as one practical next step.
LPS Real Estate Group: Cash Home Buying
LPS Real Estate Group offers Cash Home Buying for homeowners considering a direct sale to help fund long-term care. If the property needs work or preparing it for sale feels difficult during a move, its As-Is Property Acquisition may fit the situation. Creative Finance Solutions may also be relevant when a straightforward cash sale isn’t the preferred path, while Foreclosure Prevention Purchase addresses homeowners facing foreclosure concerns.
A home sale is not automatically the right choice. First consider care funding needs, legal authority to sell, Medicaid eligibility, and advice on taxes and estate plans. If those factors support selling, discuss your property and circumstances with LPS Real Estate Group. Contact LPS to discuss a direct, as-is sale and the next steps.
Make the Next Step a Deliberate One
The decision to sell a house to pay for long term care is also a decision about what the family wants the next chapter to look like. Before moving forward, agree on the priorities that matter most: supporting the homeowner’s care, respecting their preferences, and keeping relatives aligned about the home’s future. A short written plan can help everyone understand the reasons for the decision and their role in carrying it out.
If your family is still weighing options, identify the specific questions that remain and bring them to the appropriate professional. If selling feels like the right path, decide what information you need for the next step and who should be involved in the discussion. This can make a difficult transition feel more considered and manageable.
For help exploring a home sale, contact LPS Real Estate Group. Take the decision at a pace that respects your loved one and the needs of the family. A thoughtful next step can bring greater clarity to a challenging moment.
Frequently Asked Questions
Should you sell a house to pay for long-term care?
Selling may make sense if funding care is a priority and the homeowner no longer needs the property. A family selling a house to pay for long term care should compare expected proceeds with other available resources, the homeowner’s wishes, and the value of keeping the home. For example, a spouse living there may change the family’s Medicaid and housing considerations.
When Is the Right Time to Sell Your Parent’s Home to Pay for Senior Care?
The right time is when the care plan, the homeowner’s readiness, and the sale timeline can be considered together. If your parent has moved and the house is vacant, weigh the costs and effort of maintaining it against waiting for a better selling opportunity. A move date alone doesn’t settle the question. Consider whether your family has enough information to make a considered decision.
Can a person with dementia sell their house?
Yes, if the person has the mental capacity to understand and make the sale decision. A dementia diagnosis by itself doesn’t determine capacity. Consider whether the homeowner understands that the property is being sold, the main consequences, and how the decision affects them. If they can’t make that decision, a caregiver can’t simply sign in their place; legal authority must come from an applicable power of attorney or court order.
Is selling a house the best way to pay for assisted living?
Not always. A home sale can provide funds, but families may also combine savings and investments, retirement income, long-term care insurance, veterans benefits, or life insurance. Medicare doesn’t cover long-term services and supports. Compare the homeowner’s income and assets with the care plan, and consider whether keeping the home serves a housing or family purpose before deciding to sell.
How does Medicaid treat home sales when paying for senior living?
Medicaid treatment depends on the state and the applicant’s circumstances. Sale proceeds can become countable assets, so their effect on eligibility may differ from the treatment of a qualifying primary residence. If proceeds are reinvested in another Medicaid-exempt home within three months, they remain exempt. Keep sale and reinvestment records together, and consider how the timing and use of proceeds fit the care plan.
Who needs legal authority to sell the home?
The owner can sign if they have decision-making capacity. If someone else acts for the owner, a financial power of attorney must grant authority to manage real estate matters. Read its terms rather than assuming it covers a sale. If the owner can’t make the decision and no applicable power of attorney exists, a family member may need court-appointed guardianship before handling the transaction.