A foreclosure notice doesn’t mean you have to pack your bags tomorrow; it simply marks the beginning of a formal legal timeline where you still hold viable options. When relentless collection calls start coming in and confusing paperwork arrives in the mail, discovering how to avoid foreclosure fast becomes an urgent priority. It’s entirely normal to feel overwhelmed by the pressure, particularly when you’re trying to protect your credit rating and secure housing stability without immediate cash on hand.
Take a breath, because proactive solutions exist. In this guide, you will discover actionable, lender-approved strategies and rapid sale solutions to halt the foreclosure process and protect your financial future. We’ll walk through your federal rights, review loss mitigation paths, and examine direct property exit options that allow you to safeguard your remaining equity and move forward with peace of mind.
Key Takeaways
- Foreclosure operates on a structured legal timeline rather than happening overnight, giving you defined opportunities to protect your home and finances.
- Opening an immediate dialogue with your servicer’s loss mitigation department can unlock temporary payment relief, loan restructuring, or repayment agreements.
- Comparing traditional listings, short sales, and direct acquisitions clarifies the best path forward based on your home’s equity and upcoming deadlines.
- Homeowners facing impending auction dates can avoid foreclosure fast through an as-is direct property sale that eliminates financing delays and closing costs.
- Following a clear, five-step action plan restores your control, helping you safeguard your personal credit rating and walk away with your remaining equity intact.
Understanding the Foreclosure Timeline: How Much Time Do You Have?
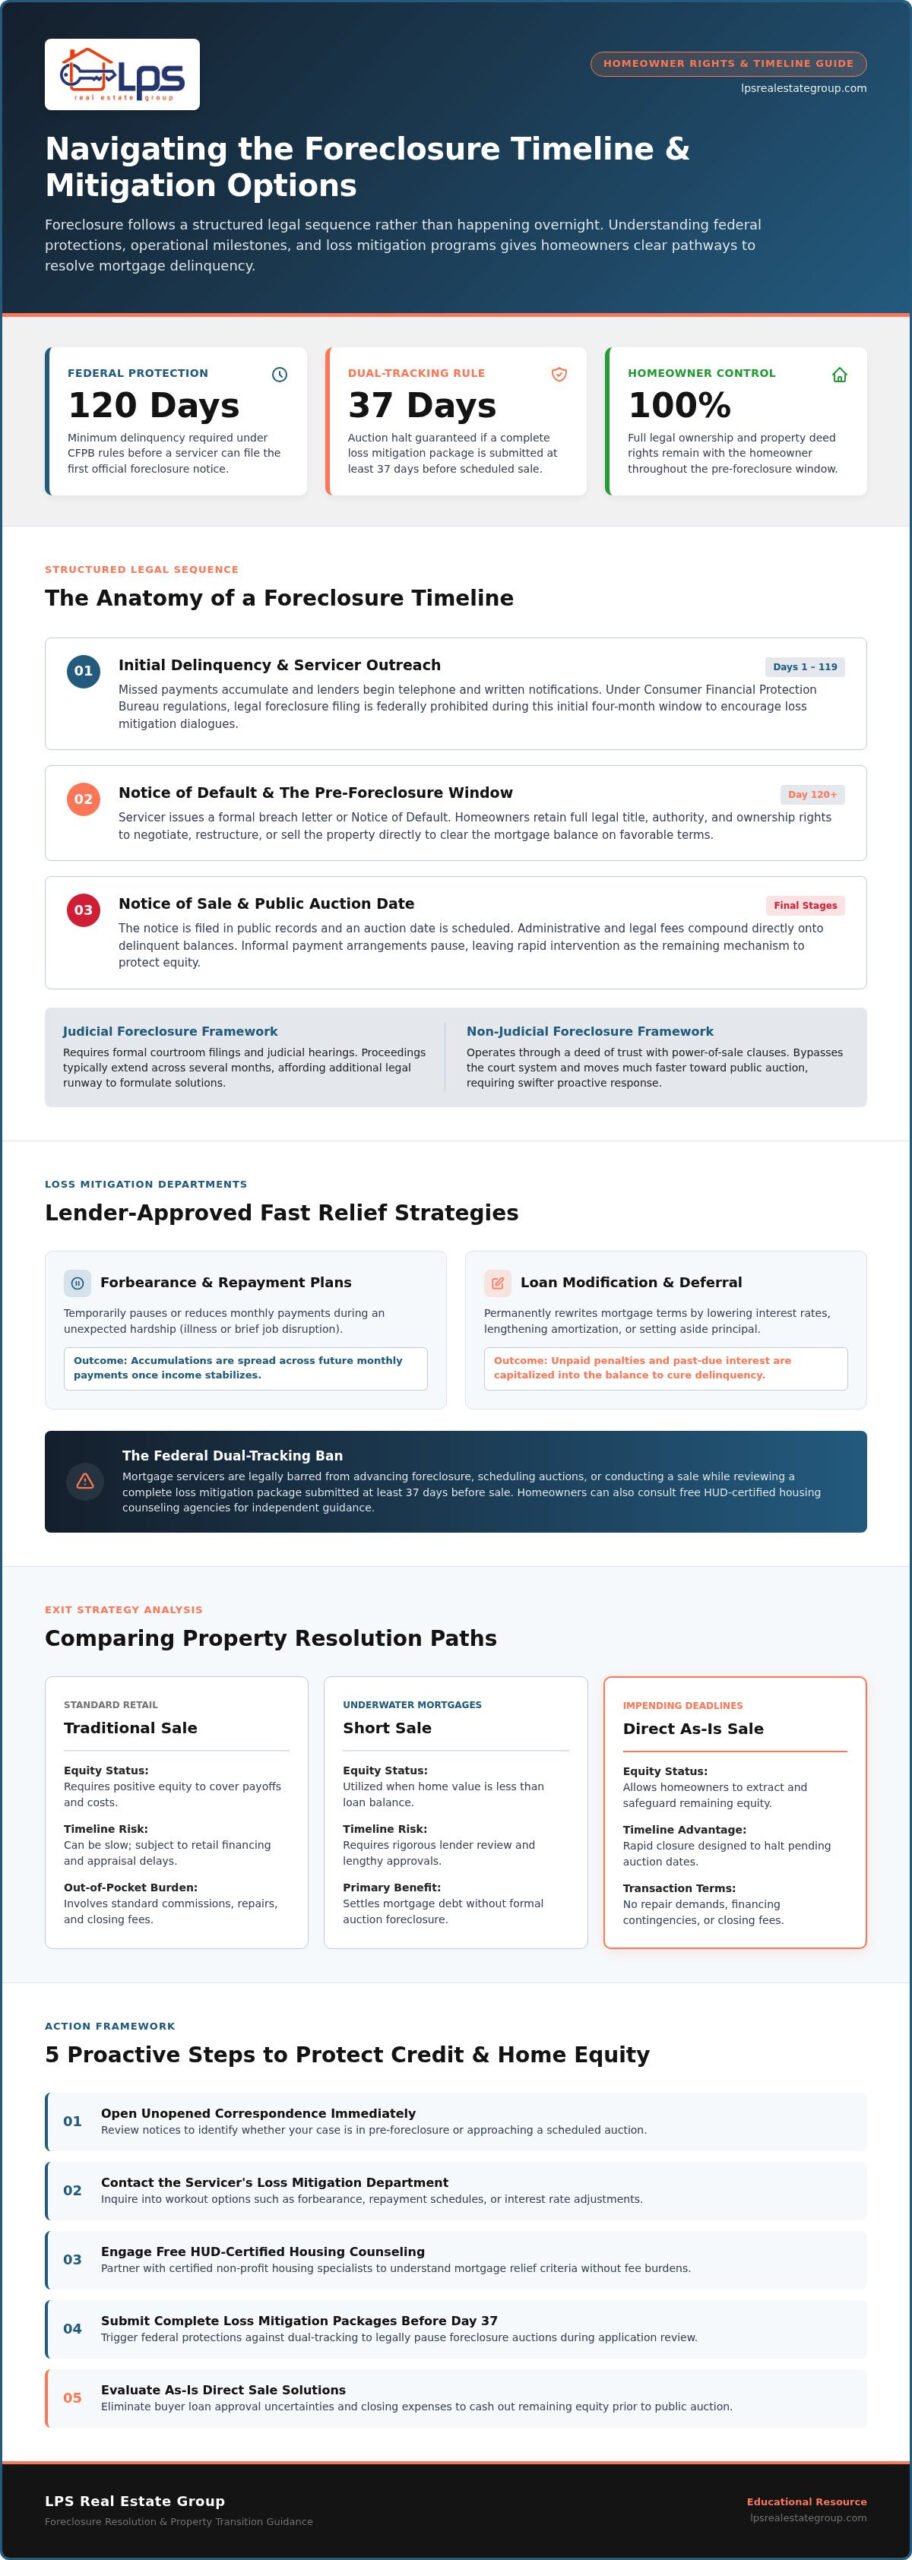
Foreclosure feels like an immediate crisis, but lenders must follow a strict legal sequence rather than seizing real estate overnight. Under federal Consumer Financial Protection Bureau regulations, a mortgage servicer generally cannot file the first official foreclosure notice until your loan is at least 120 days delinquent. This four-month window exists specifically to allow loss mitigation discussions and explore alternative exits.
Understanding the foreclosure process and whether your transaction involves a judicial or non-judicial framework clarifies your operational runway. Judicial proceedings require formal courtroom filings and often extend across several months, whereas non-judicial paths move much faster through a deed of trust. Pinpointing your current milestone is vital if you need to avoid foreclosure fast and protect your remaining equity.
The Pre-Foreclosure Window: From Missed Payment to Breach Letter
Pre-foreclosure represents the crucial window for decisive action before formal court intervention or public auction notices occur. As missed payments accumulate, servicers issue warning correspondence, culminating in a formal breach letter or notice of default. Crucially, you retain full legal ownership, title, and property rights throughout this stage. That ongoing control means you still hold the authority to negotiate, restructure, or review how to sell a house in pre-foreclosure directly to clear your outstanding mortgage debt on your own terms.
The Point of No Return: Notice of Sale and Auction
The situation changes dramatically when the mortgage servicer files a Notice of Sale and schedules a public auction date. Once this notice appears in local public records, your relief options narrow rapidly. Servicers often pause informal payment arrangements, and administrative legal fees begin compounding onto your delinquent balance. Swift intervention during these final weeks is critical to prevent your property deed from transferring to a third-party bidder. If you want to avoid foreclosure fast, acting before the auction concludes ensures you preserve your credit rating and retain whatever financial value remains in your home.
Working with Your Lender: Fast Solutions to Pause Foreclosure
Ignoring phone calls and unopened mail from your loan servicer guarantees that legal action moves forward unchecked. When you answer those calls instead, you unlock immediate options. Mortgage companies do not want your home; property repossessions cost lenders substantial time and capital. They operate dedicated loss mitigation departments tasked specifically with finding alternatives to foreclosure. Homeowners can also turn to HUD-certified housing counseling agencies, which provide non-profit, personalized support to help navigate complex lender requests for free.
Engaging directly with these representatives remains the most reliable first step to avoid foreclosure fast and freeze active collection cycles. Detailed guidance on avoiding foreclosure through structured relief programs is readily available, but acting early determines which paths stay open.
Mortgage Forbearance and Repayment Plans
A forbearance plan temporarily pauses or reduces your monthly payments during an unexpected hardship, like an illness or brief employment gap. Once your finances recover, a structured repayment plan spreads the accumulated missed balance across upcoming monthly payments until you’re current. These programs offer an ideal, low-stress bridge if your cash disruption is short-lived and your regular household income has stabilized.
Loan Modification and Principal Deferral
When long-term expenses permanently alter your budget, a loan modification rewrites the original mortgage agreement. Servicers can lower your interest rate, lengthen the amortization period, or set aside non-interest-bearing principal balances until the final payoff. Unpaid penalties and past-due interest are routinely capitalized into the new balance, instantly curing the legal delinquency upon formal approval.
Understanding the Legal Ban on Dual-Tracking
Federal lending rules strictly prohibit “dual-tracking.” Under CFPB regulations, a mortgage servicer cannot advance a foreclosure action, schedule an auction, or execute a sale while actively evaluating a complete loss mitigation application submitted at least 37 days before a scheduled auction. Submitting your complete financial file provides guaranteed legal breathing room while you assess sustainable remedies.
If lender negotiations stall or your servicer’s modification criteria prove unattainable, collaborating with LPS Real Estate Group offers a transparent exit path by purchasing your property directly to halt the auction entirely.
Traditional Sale vs. Short Sale vs. Direct Cash Sale
Selecting the right liquidation path depends entirely on your home equity and your remaining calendar days. While federal resources from HUD on Avoiding Foreclosure outline general exit alternatives, distressed homeowners often face a practical choice between three distinct transaction models. Each approach carries very different timelines, credit ramifications, and closing guarantees.
Why Traditional MLS Listings Rarely Beat Fast Foreclosures
Listing with a real estate agent on the open market demands time that distressed borrowers simply do not have. Retail buyers rely on conventional mortgages, creating 30- to 60-day underwriting delays. Deals frequently collapse over mandatory repair escrows, home inspections, and appraisal shortfalls. For a property needing repairs, learning about selling your house as-is avoids the expenses of staging and open houses while sidestepping lender repair mandates.
Short Sales: Managing Properties with Negative Equity
A short sale becomes necessary when total mortgage balances exceed the home’s fair market value. In this scenario, your servicer must explicitly agree to accept less than the full payoff amount and write off the remaining deficiency. While short sales cause less lasting damage to your personal credit score than an auction repossession, the approval process regularly drags on for several months. If your auction date is set for next week, short sale negotiations rarely move quickly enough to protect you.
Direct Cash Acquisitions: Speed and Certainty
A direct sale completely removes mortgage underwriting, home appraisals, and bank approval cycles. Direct buyers utilize private capital, which allows the sale to close in days rather than months. This method provides the speed necessary to generate immediate payoff funds and satisfy the outstanding balance with your servicer before the auction gavel falls.
Reviewing our detailed guide on how to sell my house fast for cash shows how direct acquisitions protect your credit rating. Bypassing realtor commissions and closing delays gives you an effective way to avoid foreclosure fast and walk away with your remaining home equity intact.
5 Proactive Steps to Stop Foreclosure and Protect Your Credit
Panic paralyzes decision-making, but methodical execution puts you back in control of your financial destiny. When you transition from reacting defensively to running a structured playbook, you remove the emotional noise that often delays critical choices. Early intervention turns an overwhelming legal countdown into a manageable financial transition, safeguarding both your equity and your credit score. If your goal is to avoid foreclosure fast, working through five clear milestones establishes immediate clarity.
Step 1: Request an Official Payoff and Reinstatement Quote
Your first move requires clear, unassailable financial data. Contact your mortgage servicer’s loss mitigation department and request two separate documents in writing: a formal reinstatement quote and an official payoff statement. The reinstatement quote details the exact funds needed to bring delinquent payments, late fees, and legal charges current today. The payoff statement details the full balance required to satisfy the entire loan balance. Receiving these figures in writing protects you from sudden unrecorded fees later in the process.
Step 2: Calculate Your True Net Equity Position
Take your home’s estimated market value in its current physical condition and subtract your total payoff balance, along with any secondary liens or property tax obligations. Knowing this number reveals your options clearly:
- Negative Equity: Pursue a formal loan modification, forbearance program, or negotiated short sale.
- Positive Equity: Explore an immediate property sale to capture your remaining cash value before an auction wipes it out.
Distressed homes with deferred maintenance can prove difficult to sell through conventional open-market channels. If you want to avoid foreclosure fast and walk away with your accumulated equity, an as-is transaction eliminates repair costs entirely.
Steps 3-5: Engage Experts, Select Your Exit, and Execute
With verified numbers in hand, the final three steps move swiftly. Step 3 involves consulting reputable specialists, whether that means speaking to a HUD-approved housing counselor or reviewing purchase terms with an experienced acquisitions team. Step 4 requires committing to a single exit strategy that fits your calendar deadline, whether keeping the home through restructuring or liquidating immediately. Finally, Step 5 is decisive execution: sign required agreements and instruct your closing agent to coordinate title payoff verification directly with your servicer.
When time is running short before a scheduled auction, request a direct cash buyout from LPS Real Estate Group to resolve your loan balance and secure your fresh financial start.
How LPS Real Estate Group Resolves Urgent Foreclosure Challenges
Facing an active legal countdown demands an empathetic partner with the operational capability to step in immediately. LPS Real Estate Group operates as a direct cash home buyer across the country, specializing in resolving complex pre-foreclosure challenges. Instead of dealing with the uncertainty of open-market buyers who need mortgage approvals, our direct property acquisitions eliminate financing contingencies and appraisal delays entirely. This straightforward process provides homeowners with reliable closing dates and transparent communication every step of the way.
Fast Cash Purchases to Beat Impending Auction Dates
Speed is essential when an auction date is already set on the legal calendar. We evaluate residential properties quickly to provide fair, transparent cash purchase offers without unnecessary red tape. Our team coordinates directly with established title companies and your mortgage servicer, ensuring wire payoffs arrive well before the scheduled public sale. Taking this proactive route allows you to avoid foreclosure fast, halt public proceedings, and walk away with your credit profile protected and any remaining equity in hand.
Creative Finance Solutions for Complex Debt Scenarios
Some pre-foreclosure situations involve layered challenges, such as secondary liens, overdue property taxes, or balances that closely match overall market value. When standard cash transactions do not completely satisfy your goals, explore our guide on creative real estate exit strategies. These customized debt relief structures bridge financial gaps, cure delinquency, and provide a sustainable path away from mortgage distress while keeping your long-term financial health intact.
A Dignified, As-Is Selling Experience Without Hidden Costs
We believe every homeowner deserves respect, particularly during times of acute financial stress. Selling directly to LPS Real Estate Group means you never have to worry about cleaning, repairs, or costly renovations:
- Zero out-of-pocket repairs: We purchase properties entirely as-is, regardless of physical condition or required maintenance.
- No hidden expenses: Our process bypasses traditional real estate agent commissions and unexpected administrative fees.
- Covered closing costs: We pay standard closing fees so you can maximize your net walk-away funds.
If you’re ready to review your exit options with an experienced, compassionate advisor, reach out directly for a confidential, zero-obligation consultation today.
Take Control of Your Timeline and Protect Your Future
Receiving delinquency notices can feel terrifying, but an impending auction date does not strip away your agency. As the legal timeline demonstrates, you hold viable pathways until the final gavel strikes. Whether you choose to negotiate loss mitigation terms with your servicer or liquidate property to preserve hard-earned home equity, deliberate execution is the most reliable way to avoid foreclosure fast and safeguard your long-term credit.
When conventional listing routes take too long, LPS Real Estate Group provides specialized expertise in halting pre-foreclosure timelines nationwide. Our direct as-is acquisitions bypass bank delays and standard closing fees, offering tailored creative finance and cash options delivered with genuine empathy and transparency. You don’t have to shoulder this stress alone. Request a confidential, zero-obligation cash offer to stop foreclosure today, reclaim your peace of mind, and step forward into lasting stability.
Frequently Asked Questions
Can selling my house fast really stop a foreclosure auction?
Yes, executing a direct sale can halt a foreclosure auction right up until the final sale documents are completed. A title company or settlement attorney wires certified funds directly to your mortgage servicer to satisfy the outstanding payoff amount. Once the lender confirms the loan balance is settled in full, they cancel the scheduled auction and release their legal lien against your property.
How many missed mortgage payments trigger formal foreclosure proceedings?
Under federal regulations enforced by the Consumer Financial Protection Bureau, servicers generally must wait until a borrower is at least 120 days delinquent before issuing the initial formal foreclosure filing. This four-month grace period provides crucial time to explore alternatives. Taking decisive action during these early months remains the most reliable strategy to avoid foreclosure fast before compounding legal fees inflate your debt balance.
What is the difference between a mortgage reinstatement and a payoff?
A reinstatement brings your delinquent loan back into good standing by paying only the past-due payments, accrued late fees, and servicer-incurred legal costs. In contrast, a payoff figure satisfies your entire remaining mortgage balance, completely terminating the loan agreement. You only need a reinstatement quote if you intend to keep the property, whereas selling requires a complete payoff statement.
Does a foreclosure affect my credit score worse than a short sale?
Yes, a completed foreclosure typically causes more severe and prolonged credit damage than a short sale or a timely property liquidation. A foreclosure entry can drop your credit score by 100 points or more and remains visible on public credit records for up to seven years. In contrast, liquidating your home before the auction allows you to pay off the mortgage, avoiding a public foreclosure judgment.
Can I sell my home if it requires extensive repairs and maintenance?
Yes, you can sell a property regardless of its physical condition or structural deferred maintenance by working with an as-is buyer. Conventional buyers reliant on mortgage underwriting often walk away when inspection issues arise, but direct cash home buying bypasses bank inspection standards completely. You don’t have to clean out personal belongings, repaint walls, or spend out-of-pocket cash on major repairs before closing.
What happens to my remaining equity if my house goes to auction?
If your property sells at auction for more than the outstanding debt, you are legally entitled to claim the surplus funds. However, auction bids frequently open at steep discounts, and substantial legal, auctioneer, and default fees are subtracted first. Liquidating directly prior to an auction guarantees you capture your fair equity rather than risking it during an uncertain public bidding process.
How quickly can a direct cash buyer complete a property acquisition?
A direct cash buyer can close on a residential property in as little as 7 to 30 days because the transaction bypasses conventional bank underwriting and appraisal delays. This accelerated timeline gives distressed homeowners the speed they need to intercept scheduled auction dates. Working with an experienced acquisition specialist ensures funds reach your servicer quickly, giving you a dependable way to avoid foreclosure fast.