What if the date stamped on your foreclosure notice wasn’t an inevitable end, but a deadline you could actually outrun? Most homeowners believe that once an auction is scheduled, their control over the property vanishes. However, the reality in 2026 is that you retain the legal right to sell house before foreclosure auction right up until the final bid is accepted. While average foreclosure timelines have accelerated to just 563 days, that window still provides a vital opportunity to protect your equity and your credit score.
We understand the paralyzing anxiety that comes with mounting debt and the fear of losing everything you’ve built. It’s common to feel overwhelmed by legal jargon and lender requirements; however, you don’t have to face this alone. In this guide, you’ll discover the exact steps to stop the auction clock and secure a fair outcome. We’ll show you how to navigate the current landscape, from understanding new 2026 regulations to leveraging cash offers that close in days. You can walk away with a clean slate or even some cash in hand, avoiding the long-term damage of a deficiency judgment.
Key Takeaways
- Identify the “Notice of Sale” as your most critical timeline marker and learn how to use this window to regain control of your property’s future.
- Understand the legal reality that you retain full ownership until the auction concludes, giving you the power to sell house before foreclosure auction on your own terms.
- Compare the speed of direct cash offers versus traditional buyers to see why a fast-closing, as-is purchase is often the only reliable way to outrun the auctioneer.
- Follow a clear, four-step path to secure a definitive payoff statement and a firm, no-contingency offer that settles your debt before the hammer falls.
- Discover how to protect your remaining equity and credit score by choosing a solution that requires no repairs, no commissions, and no closing costs.
Understanding the Foreclosure Auction Timeline
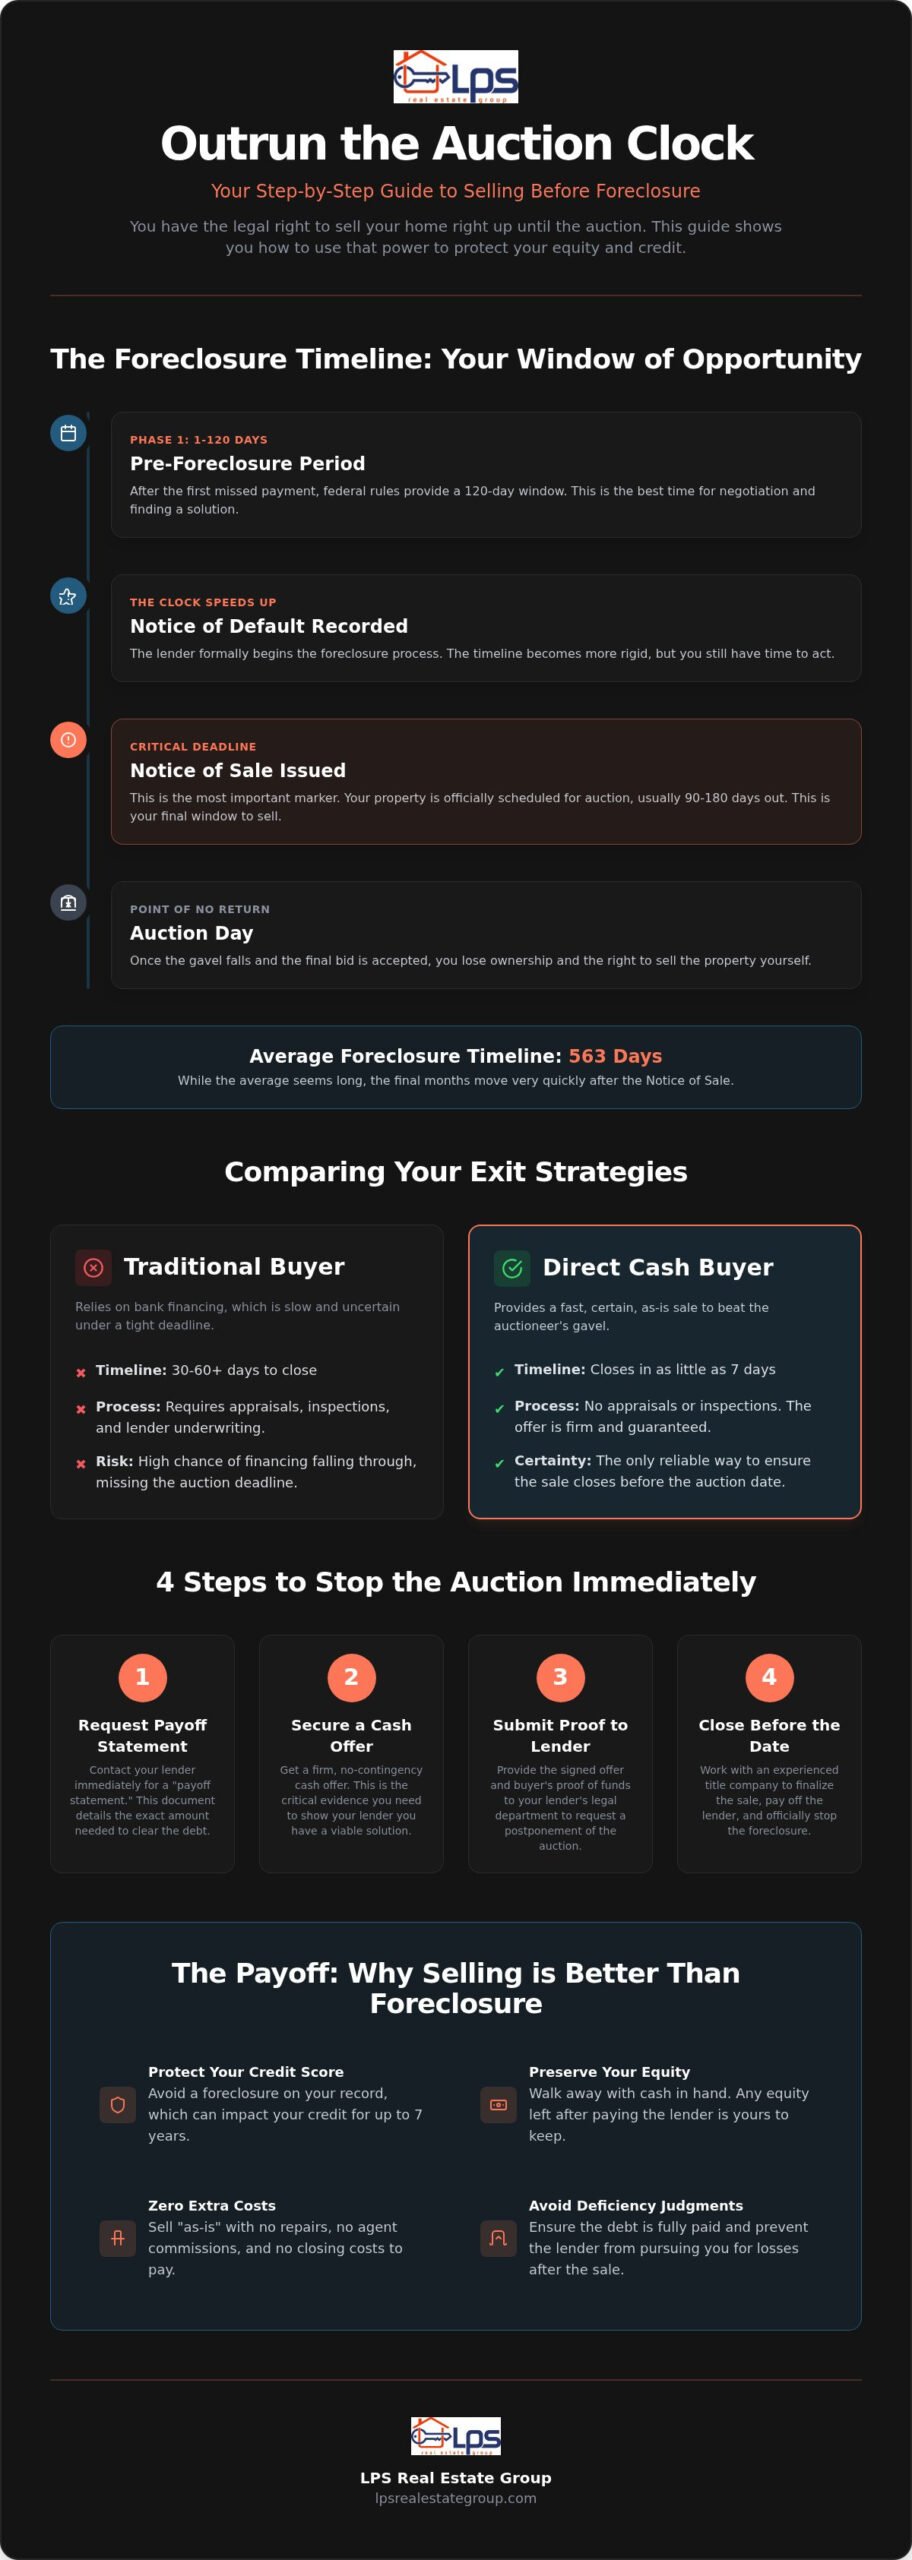
The journey from your first missed payment to a public sale isn’t an overnight event. It’s a structured legal sequence that typically begins after you’ve been delinquent for 120 days, thanks to federal consumer protection rules. Understanding the Foreclosure Process reveals that this initial “pre-foreclosure” phase is actually a window for negotiation. The clock starts moving faster once the Notice of Default is recorded, but the true deadline is the Notice of Sale. This document marks the moment your property is officially scheduled for the auction block.
Timeframes vary significantly depending on the legal requirements of your region. In non-judicial areas, the process is streamlined and can move from a notice to an auction in as little as 90 to 180 days. Judicial regions require court involvement, which often stretches the timeline to a year or longer. Across the country, the average foreclosure now takes 563 days to complete. While that might sound like a long time, the final months move quickly. Recognizing where you stand in this timeline is the first step if you want to sell house before foreclosure auction and protect your financial future.
The ‘Point of No Return’ in the Auction Process
Every homeowner should know about the “Right of Redemption.” This is your legal ability to stop the foreclosure by paying off the total debt before the sale concludes. While this right exists, waiting until the morning of the auction is a high-stakes gamble. Once the gavel falls, you lose the ability to negotiate or sell the property yourself. A completed foreclosure is a heavy burden to carry. It can lower your credit score significantly and makes it difficult to secure stable housing for years. Taking action while you still hold the deed is the only way to ensure you walk away with your dignity and credit intact.
How Lenders View a Pending Sale
Lenders are generally not interested in becoming property managers. They lose money on every house they take back through foreclosure. Because of this, most banks are surprisingly cooperative when they see a viable exit strategy. To move forward, you must request a ‘Reinstatement Quote’ or a full payoff statement. This document lists every penny needed to satisfy the lien, including late fees and legal costs. When you communicate a clear plan to sell house before foreclosure auction, the lender’s legal department may even grant a short postponement. They prefer a guaranteed payoff from a sale over the uncertainty of an auction bid any day.
Can You Actually Sell Your House Days Before the Auction?
It’s a common misconception that once the auction date is set, your rights as a homeowner disappear. The legal reality is that you own the property until the hammer falls and the deed is transferred to a new owner. This means you retain the right to sell house before foreclosure auction right up until the final moments. However, while the law is on your side, the clock is not. The primary challenge isn’t the legality of the sale, but the logistics of finding a buyer who can move fast enough to beat the deadline.
Traditional buyers who rely on bank financing are almost never an option in this scenario. A standard mortgage-backed purchase typically takes 30 to 60 days to close because of appraisals, inspections, and strict underwriting requirements. If your auction is scheduled for next week, a traditional buyer simply won’t make it to the finish line. Similarly, a short sale often becomes a trap for homeowners in a rush. While it sounds like a good solution, the bank’s approval process for a short sale can take months, which is time you don’t have when the auctioneer’s gavel is ready to fall. For more foundational advice on your options, HUD’s Guide to Avoiding Foreclosure offers a helpful starting point for homeowners in distress.
Requesting a Foreclosure Postponement
Lenders have the power to grant a “Discretionary Stay,” which is a temporary pause in the auction process. They are often willing to do this if you can prove a sale is “imminent.” To convince a lender’s legal department to stop the clock, you need a firm, no-contingency contract and a verified proof of funds from your buyer. You also need to work with a title company that understands the urgency of a foreclosure deadline. Our team at LPS Real Estate Group specializes in these high-pressure situations, providing the concrete evidence lenders need to see that a payoff is guaranteed and near.
The Risks of Last-Minute Negotiations
Never rely on a verbal promise from a customer service representative at your mortgage company. If they tell you they’ll “look into” a postponement, the auction will likely proceed as planned unless you have a written “Cancellation of Sale” or a “Notice of Postponement” in hand. The legal process is rigid, and mistakes happen in large bank departments. The equitable right of redemption is the legal bridge to a pre-auction sale, giving you the power to satisfy the debt in full through a private sale before the property is sold to the highest bidder at auction.
Comparing Your Exit Strategies: Traditional vs. Cash Buyers
When the clock is ticking toward a scheduled sale, choosing the right buyer is the most critical decision you’ll make. While many homeowners first think of a traditional real estate agent, this path is often a logistical mismatch for an auction deadline. However, consulting with a professional brokerage like Pinnacle Realty can provide essential market context, even if a traditional sale isn’t feasible. In the first half of 2026, foreclosure filings increased by 21 percent compared to last year, meaning more homeowners are competing for the attention of a limited pool of buyers. A traditional sale typically requires 60 days or more to close, which is simply too slow when you need to sell house before foreclosure auction in a matter of weeks.
Selling to a cash buyer offers a level of privacy and simplicity that the open market cannot match. You don’t have to worry about “open houses” or strangers walking through your home during an already stressful time. Most importantly, we buy houses in their current condition. You won’t need to spend money you don’t have on repairs or cleaning. You can learn more about this streamlined approach in our guide on 5 Benefits of Selling Your House to a Direct Buyer.
When a Creative Finance Solution Makes Sense
Sometimes, rising interest rates or falling property values leave homeowners with little to no equity. In these complex situations, a traditional sale might actually require you to bring money to the closing table. Creative solutions, such as “Subject-To” offers, allow a buyer to take over your existing mortgage payments. This can stop the foreclosure immediately and resolve the default faster than a standard sale. For a deeper look at these options, explore our resource on Creative Real Estate Exit Strategies.
4 Steps to Stop the Auction Clock Immediately
When the auction is only days away, timing is everything. You need a precise sequence of actions to halt the legal process and protect your interests. Many homeowners feel paralyzed by the complexity of lender requirements, but the path forward is a series of manageable steps. To sell house before foreclosure auction, you must shift from a state of worry to a state of documented action. This process requires clear communication with your lender and a buyer who can perform under pressure.
- Step 1: Request a Payoff Statement. Contact your lender immediately for an official payoff statement. This is different from your monthly balance; it includes interest, late fees, and the lender’s legal costs.
- Step 2: Secure a No-Contingency Cash Offer. You need a firm contract with a guaranteed closing date. A traditional offer with an appraisal or financing contingency will not provide the certainty a lender requires to pause a sale.
- Step 3: Submit Documentation to the Foreclosure Attorney. Once you have a signed contract and a verified proof of funds, send them to the lender’s legal representative. This is the party actually handling the auction.
- Step 4: Get Written Confirmation. Never assume the auction is off based on a phone call. You must receive a “Notice of Withdrawal” or a “Cancellation of Sale” in writing to ensure your home is safe.
Gathering Your Documentation
Lenders operate on evidence, not promises. You should have your original mortgage note and all recent correspondence from the bank organized and ready. The most important document in your arsenal is the “Proof of Funds” from your buyer. This bank statement proves the capital exists to satisfy your debt in full. A ‘Reinstatement Quote’ is the exact dollar amount needed to stop the auction. Having these numbers ready allows you to move with the speed necessary to beat a 48-hour deadline.
Coordinating with the Title Company
A standard title search can take weeks, but a foreclosure scenario requires a “rush” search. You need a title officer who understands the urgency of an auction deadline and can quickly identify any secondary liens or judgments. These unexpected hurdles must be cleared before the sale can close. We specialize in navigating these complexities and can help you secure a fast cash offer that satisfies your lender’s requirements. By using mobile or remote closing services, we ensure that the final paperwork is signed and the funds are wired before the auctioneer ever picks up the gavel.
How LPS Real Estate Group Provides a Fast Foreclosure Solution
LPS Real Estate Group operates as a specialized partner for homeowners facing the most urgent deadlines. We understand that by the time you’re looking to sell house before foreclosure auction, you’ve likely dealt with months of stressful letters and automated phone calls. Our approach is different. We don’t use aggressive sales tactics or make unrealistic promises. Instead, we provide a clear, logical path to a resolution that respects your situation and your equity. We act as a bridge between your current crisis and a stable financial future.
Our business model is built for the “as-is” reality of foreclosure. We recognize that if you’re facing a scheduled sale, you likely don’t have the funds or the time for major renovations or staging. We acquire properties in any condition, which removes the burden of repairs from your shoulders. We also handle all closing costs, ensuring that the number we agree upon is the amount you actually see at the end of the process. This transparency is a cornerstone of our service, allowing you to plan your next steps with certainty.
The LPS process is designed for maximum speed. From the moment you contact us, we can often present a firm offer within 24 hours and move toward a stopped auction in as little as 7 days. We handle the heavy lifting, including direct communication with the lender’s legal department to verify our proof of funds and intent to close. Even if your property has complex title issues, such as secondary liens or judgments, we have the experience to find a solution that works for all parties involved.
A Compassionate Approach to a Stressful Situation
As you plan your transition, coordinating the move of your belongings is just as important as the sale itself. For homeowners looking for a secure and flexible way to manage their items during this time, check out SafeHouse Storage for professional storage solutions.
We prioritize listening first. Every financial situation is unique, and we want to understand your goals, whether that’s walking away with some cash or simply avoiding the long-term credit damage of a foreclosure. Our “quiet confidence” philosophy means we provide the facts and the options, then let you decide what’s best for your family. We don’t believe in pressure; we believe in partnership. You can find more about our partner-centric model in our guide on How to Sell a House in Pre-Foreclosure.
Getting Your Fair Cash Offer Today
Starting your evaluation is a simple process that requires no upfront fees or obligations. We calculate our offers based on current market data and the specific costs required to resolve the default and handle necessary repairs. Our goal is to provide a transparent figure that accounts for the urgency of your situation while remaining fair. If you’re ready to see how we can help you Get a Fair Cash Offer and Stop Your Foreclosure Auction, reach out to our team today for a confidential consultation.
Taking Control of Your Property’s Future
The pressure of a looming auction can make it feel like your options have disappeared. However, you retain the legal right to sell house before foreclosure auction until the final bid is accepted. Success in this high stakes window depends on a clear understanding of your timeline and a buyer who can perform with extreme speed. By securing an accurate payoff statement and a firm cash offer, you can present your lender with a guaranteed resolution that stops the legal clock in its tracks.
LPS Real Estate Group is specialized in foreclosure prevention, acting as a direct cash buyer to ensure your debt is settled without the need for repairs or commissions. We buy properties as-is, allowing you to bypass the traditional market’s delays and walk away with a clean slate. Don’t let the clock run out on your home equity or your credit score. Stop your foreclosure auction today with a fair cash offer from LPS Real Estate Group. You have the power to change the outcome of this situation, and we’re here to provide the steady, professional guidance you need to move forward with confidence.
Frequently Asked Questions
Can I sell my house the day before the foreclosure auction?
Yes, you can legally sell your property up until the moment the gavel falls. While you still hold the deed, you have the right to transfer it to a buyer. The challenge is the speed of the transaction. You must ensure the lender’s legal team receives the payoff funds before the auction begins. Working with a specialist who can close quickly is the most reliable way to sell house before foreclosure auction at the eleventh hour.
What happens to my equity if the house goes to auction?
If your home sells at auction, any equity you’ve built is at significant risk. Auctions often result in sale prices far below fair market value. While you are legally entitled to surplus funds if the sale price exceeds your total debt, these funds are frequently depleted by mounting legal fees and lender costs. Selling the property yourself before the auction allows you to control the price and preserve your hard-earned equity.
Will selling my house stop the foreclosure from appearing on my credit report?
Selling your home won’t remove the history of missed payments already reported to credit bureaus. However, it prevents the most damaging mark: a completed foreclosure. A foreclosure status can drop your credit score by 100 points or more and remains on your report for seven years. By selling early and paying off the debt, the account is marked as paid, which is far less harmful to your future borrowing power.
Do I need my lender’s permission to sell my house before the auction?
You don’t need formal permission if the sale price covers your entire mortgage balance plus any accrued interest and legal fees. In this case, you are simply exercising your right to pay off the loan. However, if the sale price is less than what you owe, you are entering short sale territory. This requires the lender’s specific approval because they are agreeing to take a loss on the loan to avoid an auction.
What is a deficiency judgment, and can selling early prevent it?
A deficiency judgment is a legal ruling that allows a lender to collect the remaining balance if an auction sale doesn’t cover your total debt. This can lead to wage garnishments or bank account levies. When you sell house before foreclosure auction for the full payoff amount, you eliminate this risk entirely. It ensures the debt is settled once and for all, providing you with a clean financial slate and peace of mind.
Can I still sell my house if I owe more than it’s worth (underwater)?
Yes, homeowners with little to no equity have several options. You might pursue a short sale with lender approval or explore creative finance solutions. Creative options involve a buyer taking over your existing mortgage payments. This can be a faster alternative to a traditional sale when you’re underwater. These strategies prioritize stopping the foreclosure and protecting your credit over walking away with cash.
How fast can a cash buyer actually close a foreclosure sale?
A professional cash buyer can typically close a transaction in 7 to 14 days. This speed is possible because cash purchases skip the lengthy requirements of traditional bank appraisals and mortgage underwriting. We have streamlined our process to handle urgent auction deadlines. We focus on rapid title searches and immediate funding to ensure the sale is finalized and the lender is paid before the auction date arrives.
What is the difference between a pre-foreclosure sale and a short sale?
Pre-foreclosure refers to the period between your first missed payment and the final auction date. It’s a timeframe, not a specific type of sale. A short sale is a financial arrangement where the lender agrees to accept less than the full amount owed. You can have a standard pre-foreclosure sale if you have equity, or a short sale if you don’t. Both are effective ways to avoid the auction process.