What if the highest offer on your home isn’t actually the one that puts the most money in your bank account? It’s a common trap in 2026. Sellers often get fixated on a big number on the MLS, only to see it chipped away by commissions, repair demands, and months of holding costs. Deciding between a cash offer vs listing on MLS is no longer just about the sale price; it’s about the reality of your situation. You might feel the weight of a house that needs work or the anxiety of waiting for a buyer’s financing that might never close. We understand that stress. You want a path that respects your time and protects your hard-earned equity without the constant pressure of keeping your home stage-ready for strangers.
This guide helps you look past surface numbers to see the real-world impact of both choices. We’ll break down the hidden costs of traditional selling, from the 5.7% average commission to the risk of the one in seven contracts that face delays. You’ll discover how a direct sale can provide a guaranteed closing date and eliminate out-of-pocket repairs entirely. By comparing these paths side-by-side, you can choose the strategy that offers the most net proceeds and the most peace of mind for your specific needs.
Key Takeaways
- Understand how the competitive “beauty contest” of the 2026 MLS differs from a direct, as-is sale to help you prioritize speed over market exposure.
- Calculate your true net proceeds when weighing a cash offer vs listing on MLS by accounting for agent commissions and monthly holding costs.
- Identify the hidden financial risks of traditional listings, such as the high cost of lender-required repairs and the uncertainty of buyer financing.
- Discover why time-sensitive situations like probate or foreclosure prevention benefit from the transparency and certainty of a direct property acquisition.
- Apply a practical three-question checklist to determine which selling method protects your equity while providing the most peace of mind.
Cash Offer vs. Listing on MLS: Understanding the Two Paths
The real estate market in 2026 has evolved into a space where strategy matters just as much as the property itself. With the average 30-year fixed mortgage rate sitting at 6.66%, buyers are more selective and less likely to overlook minor flaws. This shift means your decision between a cash offer vs listing on MLS will dictate not just your final check, but the amount of stress you endure during the process. You are essentially choosing between two very different philosophies: the public marketplace and the direct acquisition.
The fundamental trade-off lies in the balance between marketplace exposure and transactional certainty. A public listing aims for the widest possible audience, hoping to spark a bidding war. Conversely, a direct offer focuses on a guaranteed result with a fixed timeline. Understanding how these paths function is the first step toward protecting your equity.
What Exactly is the MLS?
The Multiple Listing Service (MLS) is the primary engine behind traditional real estate. It is a private database where licensed agents share property details, which then syndicate to public-facing websites like Zillow and Realtor.com. In this model, you typically work with a listing agent who handles marketing, while a buyer’s agent represents the other side. This process relies on a chain of events, including open houses, professional photography, and buyer financing approvals. For those who choose this route, partnering with an expert like Lisa Hansen Realtor ensures that your home is positioned correctly to attract qualified buyers in the competitive residential market.
The MLS is a competitive bidding environment that requires the home to be in ‘market-ready’ condition. This means you must often invest in repairs or staging before the first viewer even walks through the door. If your home doesn’t meet the “beauty contest” standards of 2026 buyers, it may sit on the market, leading to price drops and increased holding costs.
A professional cash offer provides a direct alternative to the public market. Instead of searching for an individual buyer who needs a bank loan, you work with groups like LPS Real Estate Group that use internal capital to purchase homes. This bypasses the need for traditional bank appraisals, which are one of the most common reasons deals fall through in today’s market.
Because these buyers don’t rely on mortgage approvals, they can offer a level of speed that the traditional market cannot match. A cash offer is often called a ‘hassle-free’ sale because it removes the most painful parts of the process. There are no public showings, no “stage-ready” requirements, and no waiting for a lender’s green light. This path is built for sellers who value their time and need a predictable, transparent outcome without the noise of the open market.
The Realities of Listing on the MLS in 2026
Listing on the open market in 2026 often feels like entering a high-stakes beauty contest. Because inventory levels have shifted, your property isn’t just competing with the house down the street; it’s competing with brand-new constructions that offer modern warranties and “smart” floor plans. This creates a challenging environment for owners of older properties or homes that need a bit of love. When you evaluate a cash offer vs listing on MLS, you have to consider if your home can realistically win over a buyer who has a dozen other “perfect” options at their fingertips.
The unpredictability of the “Days on Market” metric adds another layer of stress to the cash offer vs listing on MLS debate. While a financed offer typically takes 30 to 45 days to close once under contract, getting to that contract can take months. During this time, you are responsible for every mortgage payment, utility bill, and tax installment. These holding costs quietly drain your equity while you wait for the “perfect” buyer to appear. It’s a gamble that doesn’t always pay off, especially if market conditions shift while you’re waiting.
Preparation and Showings: The Hidden Workload
The traditional path demands your home stay in pristine condition. This means deep cleaning every weekend, investing in professional staging, and paying for high-end photography to stand out online. Then come the showings. You might receive a request with only thirty minutes of notice, forcing you to scramble and vacate your own home. It’s exhausting to maintain this level of readiness, especially when many “looky-loos” who tour the property aren’t even qualified to make an offer. You invest significant emotional and physical energy into people who may never sign a contract.
Lender Requirements and Appraisal Hurdles
Even after you find a buyer, the “Inspection Trap” begins. Buyers using FHA or VA loans often face strict lender requirements. If the inspector finds a peeling shingle or an outdated electrical panel, the bank may refuse to fund the loan until you pay for repairs out of your own pocket. There is also the risk of an appraisal gap. If the bank’s appraiser values your home lower than the buyer’s offer, the deal can stall or collapse entirely. Roughly one in seven purchase contracts experience delays, often due to these financial hurdles.
Choosing a different route, such as selling a house as-is, removes these obstacles. You don’t have to worry about bank approvals or repair lists. If the traditional process feels like too much of a gamble, reaching out to LPS Real Estate Group for a direct quote might be the steady, reliable solution you need.
The True Cost of Selling: A Net Proceeds Comparison
When you evaluate a cash offer vs listing on MLS, it’s easy to get distracted by the top-line number. Many sellers focus on the gross sale price, but that figure rarely represents what you actually get to keep. In the 2026 market, the gap between the contract price and your net proceeds has widened. You have to account for commissions, closing fees, and the “repair deductible” that surfaces after a home inspection. These costs can quickly strip away 10% to 15% of your home’s value before you ever reach the closing table.
Holding costs are the silent equity killers. Every month your house sits on the market, you’re paying for the mortgage, property taxes, insurance, and utilities. If a traditional sale takes four months from listing to closing, those monthly bills represent money that could have stayed in your pocket. Additionally, buyers in 2026 are increasingly savvy, often requesting up to 3% in closing cost assistance as a condition of their offer. These concessions, combined with standard agent fees, mean the “winning” offer on the MLS might not be the most profitable one for your family.
MLS Listing Math: A Hypothetical Breakdown
Let’s look at a hypothetical $400,000 sale on the open market. First, you’ll likely pay a national average commission of approximately 5.7%, which totals $22,800. Next, add roughly 2% for your share of closing costs and another 3% for buyer concessions. That’s another $20,000 gone. If the house sits for four months with holding costs of $2,500 per month, you lose an additional $10,000. After subtracting these expenses, your $400,000 “high offer” has dwindled to a net check of roughly $347,200. A lower cash offer can often result in a similar net check when commissions and repairs are removed.
Cash Offer Math: Transparency and Certainty
Contrast that traditional path with a direct cash offer. If you receive a $360,000 cash offer, the math is refreshingly simple because the deductions are virtually non-existent. You pay zero real estate commissions and zero closing costs. There are no repair requests because the property is purchased exactly as it stands today. You also stop the “bleeding” of holding costs immediately. Instead of waiting 120 days for a financed deal to clear, you can close in as little as 7 to 14 days. This speed doesn’t just save you stress; it preserves thousands of dollars in carrying costs. When you compare the final numbers, the certainty of a direct sale often provides a more stable financial foundation for your next chapter.
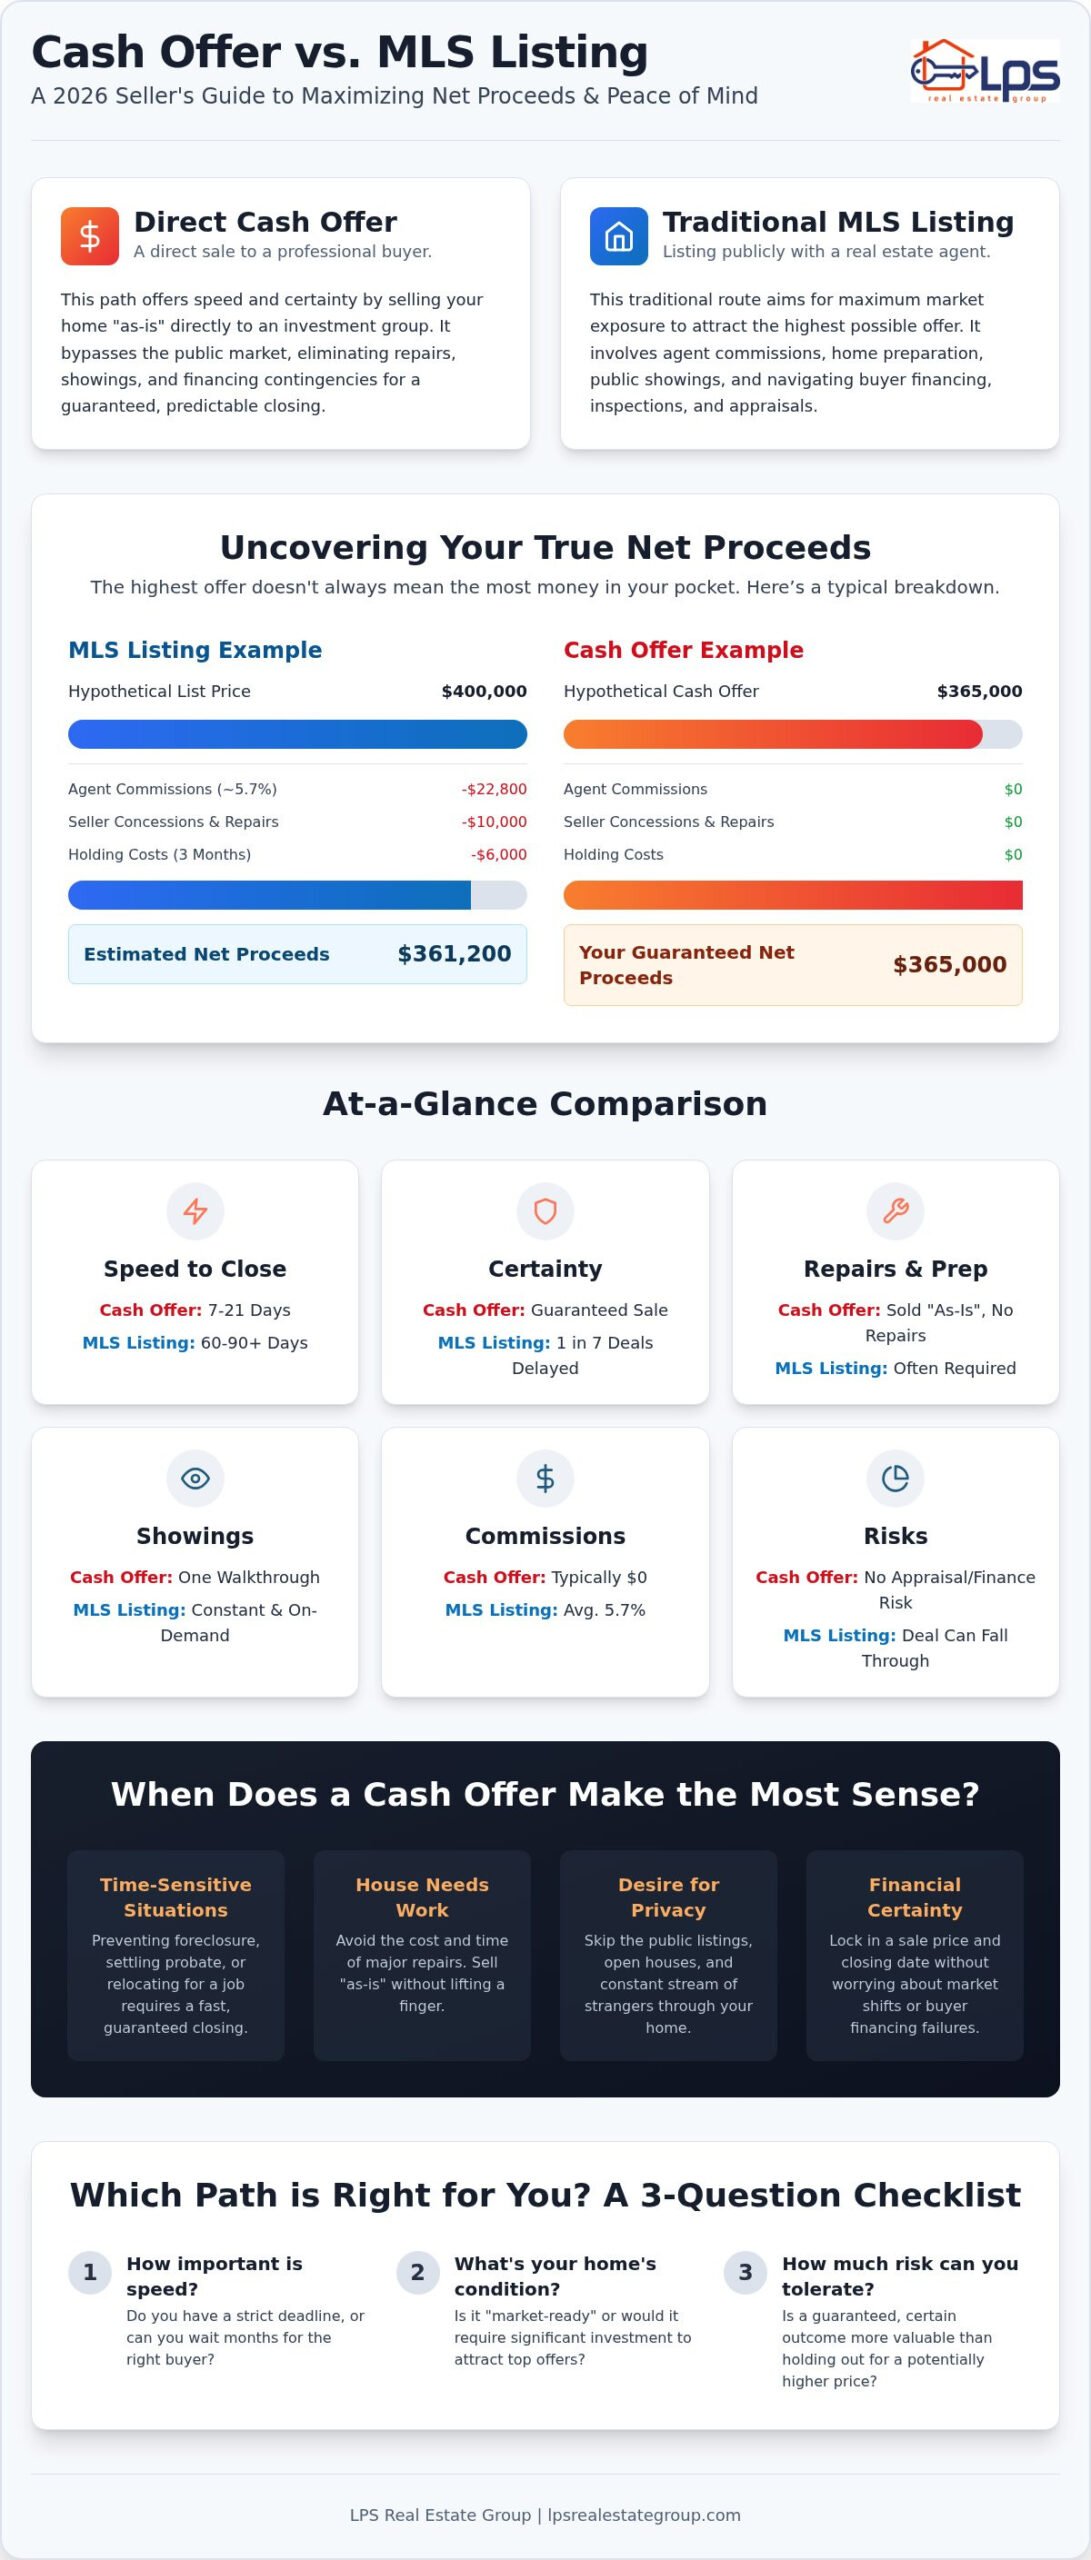
When Certainty Wins: Scenarios That Favor a Cash Offer
While the financial math we explored earlier is vital, some life situations demand a solution that the public market simply cannot provide. In these moments, the debate between a cash offer vs listing on MLS shifts from a purely financial calculation to a search for stability. Life doesn’t always wait for a 45-day mortgage approval process to finish. Whether you’re managing probate and inherited properties from a distance or need urgent foreclosure prevention to protect your credit, the value of a guaranteed closing date is immeasurable.
Speed and simplicity are often the highest priorities during a divorce or a sudden job relocation. These transitions are already emotionally taxed; adding the stress of open houses and picky buyers can be overwhelming. A direct sale allows you to close the door on a difficult chapter in days rather than months. You get to skip the “beauty contest” and focus on your next move.
The Burden of Distressed Real Estate
Traditional buyers in 2026 are looking for move-in-ready homes. If your property has structural issues, code violations, or is a hoarder situation, it likely won’t qualify for traditional financing. Companies that buy houses for cash specialize in these “un-listable” homes, taking on the burden of massive repairs so you don’t have to. There is a profound sense of relief in walking away from a problem property exactly as it stands, without spending a single dollar on renovations or cleaning services.
Creative Finance: An Alternative for Low-Equity Sellers
Not every seller has a mountain of equity to lean on. If you purchased your home recently or owe more than the current market value, a traditional sale might require you to bring cash to the closing table just to pay the agent commissions. This is where creative exit strategies become essential. LPS Real Estate Group uses tools like “Subject-To” or owner financing to create winning outcomes for sellers with low equity. These solutions allow you to move on from a property without the financial sting of a traditional listing, even when the numbers seem impossible.
If you’re managing a complex property situation and need a clear path forward, contact LPS Real Estate Group for a transparent, no-pressure assessment of your options.
Making the Right Choice for Your Future
Deciding on a cash offer vs listing on MLS is ultimately about aligning your selling strategy with your current life goals. While the traditional market is a powerful tool for certain homes, it isn’t a universal solution. If you determine that your property is a strong candidate for the open market, you can visit Congress Realty to learn about their full-service listing solutions designed to streamline the traditional sale. To help you find the right path, we suggest a simple three-question checklist. First, do you have the time to wait several months for a financed deal to close? Second, do you have the liquid cash to handle potentially expensive repairs? Third, is your home’s condition strong enough to pass a strict 2026 bank appraisal? If these hurdles feel overwhelming, the direct path may offer the relief you need.
Transparency is the most important quality to look for in a direct buyer. A legitimate partner will provide proof of funds and won’t use high-pressure tactics to force a signature. They should be willing to explain their process and how they reached their offer. At LPS Real Estate Group, we prioritize this “listener-first” approach. We understand that you aren’t just selling a building; you’re transitioning out of a significant part of your life, and that deserves respect and integrity.
Every seller has a different “north star.” For some, the primary goal is chasing the highest possible gross number, even if it takes six months of showings and thousands in renovations. For others, the priority is the certainty of a “done” sale. In a fluctuating 2026 market, waiting too long can be a gamble. A direct acquisition provides a fixed result today, protecting your equity from future market dips and the stress of constant property maintenance. Choosing peace of mind doesn’t mean you’re leaving money on the table; it means you’re valuing your time and avoiding the hidden costs we discussed earlier.
How to Get Started with a No-Pressure Consultation
Our process is designed to be straightforward and respectful. It begins with a simple request for a consultation, followed by a brief, low-stress property walkthrough. We look at the home’s potential and provide a fair, no-obligation offer based on its current condition. You don’t have to worry about cleaning, staging, or fixing a single thing before we arrive.
The most important part of our approach is that you remain in control of the timeline. Whether you need to close next week to resolve a financial hurdle or need another month to organize an inherited estate, we work at your pace. We handle the paperwork and the logistics, allowing you to focus on your next move. If you’re ready to explore a path that prioritizes your peace of mind, we’re here to listen and provide a clear, honest solution.
Secure Your Financial Path Today
Choosing between a cash offer vs listing on MLS doesn’t have to be a source of anxiety. It’s about finding the balance that fits your current life. While the traditional market rewards patience and “market-ready” homes, direct acquisitions offer a vital lifeline for those needing speed and simplicity. If you’re managing an inherited estate or trying to prevent foreclosure, the certainty of a guaranteed closing date often outweighs the gamble of a public listing.
Our team brings deep expertise in probate buyouts and creative finance solutions to ensure you aren’t left behind by shifting market trends. We focus on a transparent as-is acquisition process that respects your equity and your time. You deserve a partner who listens first and provides a clear, manageable path forward. Whether you need to close quickly or simply want to avoid the stress of renovations, we’re ready to help.
Get your fair, no-obligation cash offer from LPS Real Estate Group today. We’re here to help you move into your next chapter with confidence and peace of mind.
Frequently Asked Questions
Is a cash offer always lower than an MLS listing price?
A cash offer is not always lower than what you would keep from an MLS listing. While the gross offer might be lower, it eliminates the 5.7% average commission and standard closing costs. In the cash offer vs listing on MLS comparison, your net check is often similar because you avoid expensive repairs and months of holding costs. This transparency allows you to see exactly what you will keep without hidden deductions.
How long does it take to get a cash offer vs. listing on the MLS?
A direct buyer can typically provide a cash offer within 24 to 48 hours of a brief property walkthrough. In contrast, listing on the MLS involves significant preparation, staging, and professional photography before the house even goes live. While a cash sale can close in as little as 7 to 14 days, traditional financed offers in 2026 often take 30 to 45 days just to clear the bank’s underwriting process after a contract is signed.
Will I have to pay any fees if I accept a cash offer?
You typically won’t pay any fees when you accept a direct cash offer. This process eliminates real estate agent commissions, which can save you a significant portion of your equity. Additionally, reputable buyers like LPS Real Estate Group cover the standard closing costs. This straightforward approach ensures that the number on your contract is the actual amount you receive at the end of the transaction, providing a sense of relief and financial clarity.
Can I sell my house for cash if it’s currently in foreclosure?
You can absolutely sell your house for cash if it is in foreclosure. Selling to a direct buyer is a common strategy for foreclosure prevention because it provides the speed needed to stop an auction. This process allows you to pay off your mortgage balance quickly and protect your credit score from long-term damage. It is a compassionate way to resolve a difficult situation while potentially walking away with your remaining home equity.
What repairs are required before selling to a direct buyer?
No repairs are required before selling your home to a professional direct buyer. We specialize in as-is property acquisitions, meaning we take on the responsibility for all structural, cosmetic, or code issues. You don’t need to paint, deep clean, or fix a leaky roof before the sale. This removal of the repair deductible is a major factor for many when choosing a cash offer vs listing on MLS, especially for older properties.
How do I know if a cash home buying company is legitimate?
A legitimate cash home buying company will always be transparent about their process and provide verifiable proof of funds. They should never pressure you into a quick decision or ask for money upfront. Look for a professional presence and a history of resolving complex issues like probate or foreclosure. Honest buyers prioritize listening to your specific needs and will explain exactly how they calculated their offer without using confusing industry jargon or hidden clauses.
Can I list on the MLS after receiving a cash offer?
You are free to list on the MLS even after receiving a cash offer. A reputable buyer provides a no-pressure, no-obligation quote that you can use as a baseline for your decision. However, you should remember that listing on the open market involves new costs, such as agent commissions, staging, and ongoing holding costs. You must weigh the potential for a higher gross price against the certainty and immediate speed of the direct offer.
What are the closing costs when selling to an investor?
In a typical direct sale, the buyer covers the majority of the closing costs. This includes expenses such as title insurance, recording fees, and transfer taxes. While a traditional seller on the MLS might pay between 1% and 3% of the sale price in closing fees, a direct acquisition removes this financial burden. This policy is part of a commitment to transparency, ensuring you know your exact net proceeds from the very beginning of the process.