What if the highest offer on your home actually leaves you with less money and more stress? In the 2026 real estate market, where houses are sitting longer and mortgage rates remain elevated, the traditional path isn’t always the smoothest one. You’ve likely felt the weight of an endless to-do list of repairs or the anxiety of waiting for a buyer’s financing to clear. It’s natural to weigh the pros and cons of selling to a cash home buyer when you need a certain outcome without the typical hurdles.
We understand that your home is your most significant asset, and the fear of being scammed or undervalued is real. Our goal is to provide a transparent look at how these transactions work today. We’ll explore the honest trade-offs of cash sales, from the potential for a 7 to 14 day closing to the impact of new 2026 FinCEN reporting rules. You’ll discover if the speed and simplicity of an as-is sale outweigh the potential for a higher price on the open market. This breakdown will help you move forward with clarity and quiet confidence.
Key Takeaways
- Learn how a cash sale can close in as little as 7 to 14 days, providing immediate relief in a slowing 2026 market.
- Understand the pros and cons of selling to a cash home buyer, specifically how trading a portion of equity can eliminate the need for costly repairs.
- Identify common red flags to help you distinguish legitimate professional buyers from predatory wholesalers or potential scams.
- Discover how creative finance solutions can offer a strategic middle ground, often resulting in a higher price than a standard cash offer.
- Use our simple framework to decide if your property condition and your personal timeline make a direct sale the right move for your family.
What is a Cash Home Buyer and How Does the Process Work?
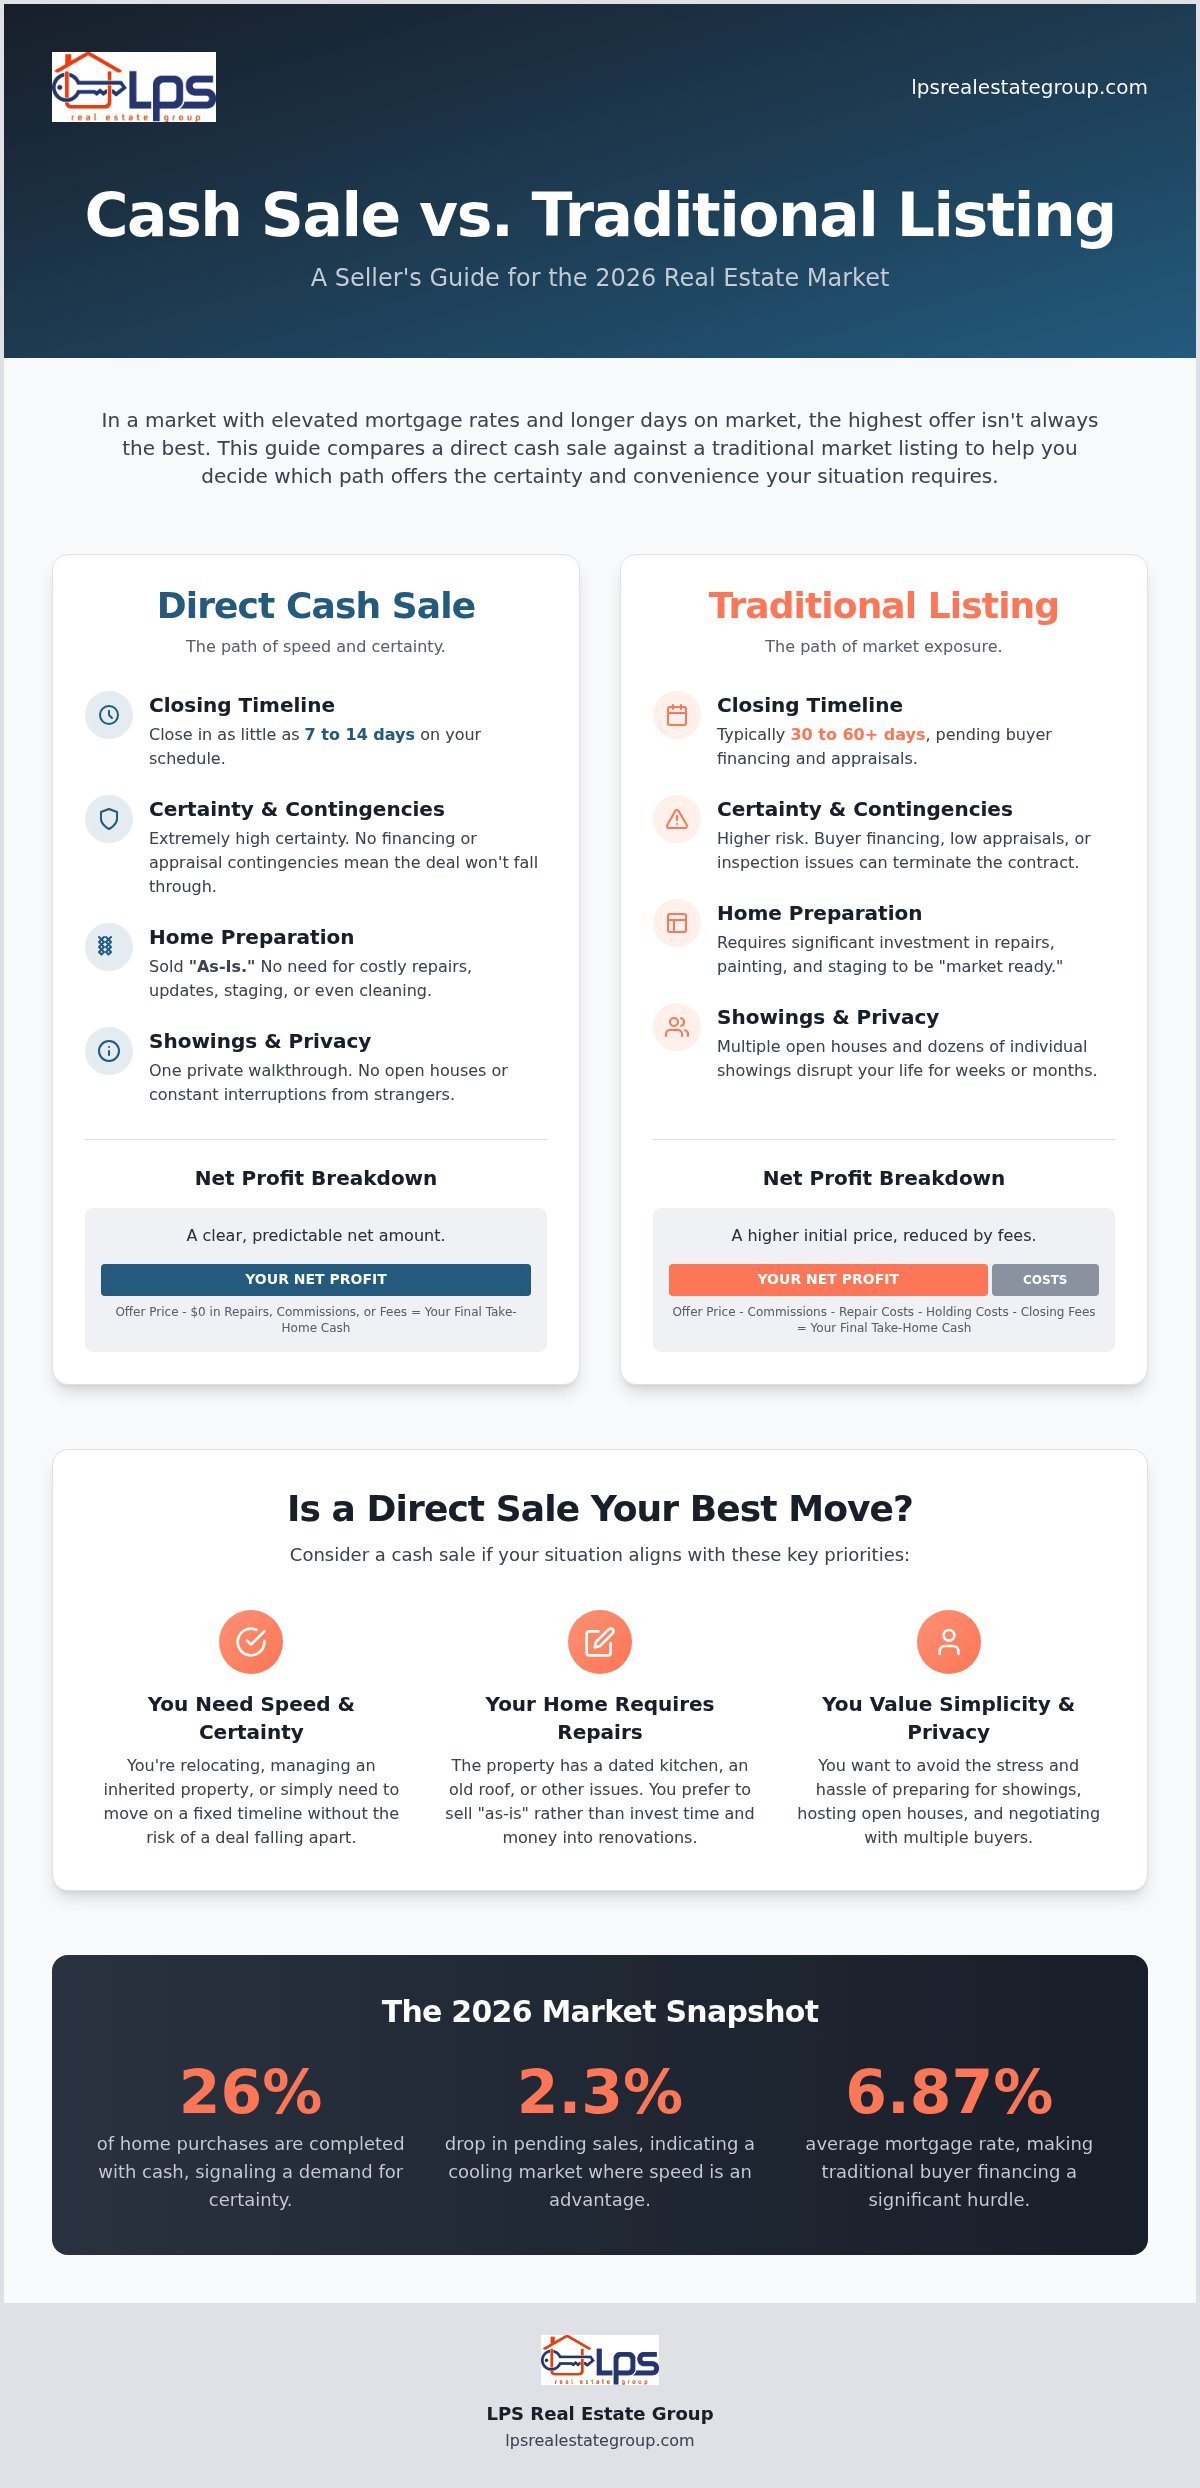
A cash home buyer is an individual or entity that has the full purchase price available in liquid funds. Unlike a traditional buyer who relies on a bank loan, these buyers provide a “proof of funds” letter instead of a mortgage pre-approval. This distinction is vital when weighing the pros and cons of selling to a cash home buyer. In 2026, roughly 26% of all home purchases are completed with cash, reflecting a steady trend toward speed and certainty in a market where pending home sales have dipped.
You’ll encounter several types of cash buyers. Some are “iBuyers,” which are large tech companies using algorithms to price homes. Others are local house flippers looking for a project. Professional investment groups, such as LPS Real Estate Group, focus on direct property acquisition and often handle complex situations like probate or inherited homes. These groups typically specialize in “as-is” purchases, meaning they won’t ask you to fix the roof or update the kitchen before closing.
The Difference Between Cash Buyers and Traditional Buyers
The primary currency in a cash transaction isn’t just money; it’s certainty. In a traditional sale, a buyer’s mortgage contingency can sink the deal at the last minute if the bank’s appraisal comes in low or the buyer’s credit score shifts. What is a Cash Offer? At its core, it’s a promise backed by immediate liquidity. Because there’s no bank involved, the need for a formal appraisal or a multi-week underwriting process disappears. This allows the seller to bypass the “appraisal gap” stress that often plagues traditional listings in 2026. It’s a straightforward path that prioritizes your peace of mind over bureaucratic red tape.
The Typical Cash Sale Timeline in 2026
While a standard market listing often takes 30 to 60 days to close, a cash sale moves at your pace. This efficiency is why many homeowners choose this path during urgent situations like probate or foreclosure. Here is how the process usually unfolds:
- Step 1: Initial Inquiry: You share basic details about your property’s condition and your goals.
- Step 2: The Walkthrough: A representative visits the home to assess its “as-is” value. They aren’t looking for perfection; they’re looking at the potential.
- Step 3: Offer and Review: You receive a formal offer. In 2026, this includes transparent contract terms that account for new FinCEN reporting rules, which require transparency for transactions involving legal entities like LLCs.
This streamlined approach means you could have funds in hand in as little as 7 to 14 days, providing a clear path forward when time is of the essence. It removes the guesswork and replaces it with a firm date on the calendar.
The Pros: Why Selling for Cash is the Preferred Path for Many
While the 2026 market shows national home values growing at a modest 1.4%, the reality for many sellers is a cooling environment where pending sales have dropped by 2.3%. In this climate, the most significant advantage of a cash offer is the elimination of market volatility. When you choose a cash buyer, you aren’t just selling a property; you’re buying back your time and certainty. This is a core part of the pros and cons of selling to a cash home buyer. You bypass the months of waiting for a buyer who might struggle with a 6.87% mortgage rate, and instead, you move directly to a guaranteed closing.
The “as-is” nature of these deals provides a level of relief that a traditional listing cannot match. You won’t need to spend weekends painting, landscaping, or managing a major kitchen remodel just to attract a buyer. There’s no need for staging or the intrusion of multiple open houses. Instead, you receive a transparent offer that accounts for the home’s current state, allowing you to walk away without further investment or effort.
Avoiding the Hidden Costs of Traditional Selling
Traditional sales often come with “carrying costs” that eat into your equity every month the house sits on the market. These include property taxes, homeowners insurance, and utilities, which can add up to thousands of dollars over a typical four to five month listing period. Additionally, many sellers fall into the “inspection trap.” This happens when a traditional buyer uses a professional inspection report to renegotiate the price downward or demand expensive repairs just days before closing. By choosing Selling Your House As-Is: The Complete 2026 Homeowner’s Guide, you avoid these surprises and keep your financial planning on track.
Solving Complex Real Estate Problems
Cash buyers provide a vital exit strategy for homeowners facing time-sensitive or emotionally heavy situations. If you’re trying to stop a foreclosure, the 7 to 14 day closing window can be the difference between losing your equity and walking away with a fresh start. Similarly, for those How to Sell an Inherited Property: A Complete Guide for Heirs and Executors, a cash sale simplifies the process by removing the need for family members to agree on repair budgets or renovation styles. It’s a compassionate way to liquidate assets quickly so everyone can move forward. If you’re facing a complex situation, you might want to explore a direct property acquisition to see how a certain closing can resolve your specific hurdle.
The Cons: Understanding the Trade-offs of a Cash Offer
Every strategic decision involves a trade-off. When evaluating the pros and cons of selling to a cash home buyer, it’s essential to look closely at the financial and emotional costs. While the speed of a 14-day closing is attractive, it usually means accepting a lower purchase price than you might receive on the open market. This is the “convenience fee” for certainty. In 2026, where home value growth is forecasted at a slim 0.3%, every dollar of equity matters. You must decide if immediate liquidity is worth the reduction in gross sale price.
Missing out on market exposure is another significant factor. A traditional listing puts your home in front of hundreds of potential buyers. Some of these are emotional buyers who might fall in love with your backyard or kitchen and bid above the asking price. Cash investors don’t buy with emotion; they buy with spreadsheets. They prioritize their own profit margins and renovation costs. This means they won’t participate in a bidding war that drives the price higher. For some, the fast pace of these offers can also feel overwhelming, leaving little time to process the transition.
The Price vs. Value Equation
It’s easy to get fixated on the gross offer price, but the net proceeds tell the real story. In a traditional sale, you’ll likely pay 5% to 6% in agent commissions, plus another 1% to 3% in closing costs. When you add the cost of repairs and the “stress tax” of keeping your home show-ready for months, the gap between a cash offer and a traditional net profit often shrinks. Understanding the pros and cons of selling to a cash home buyer helps you see that the best offer isn’t always the highest one; it’s the one that actually reaches the finish line without unexpected deductions. If your home is in pristine condition in a high-demand area, a traditional listing might still be your best financial move. For those in specific markets, such as homeowners looking for a makelaar Lent in the Netherlands, professional local guidance can help you determine if the traditional route will indeed yield the highest net return. However, if the property needs significant work, the math often tips in favor of the cash buyer.
The rise of wholesalers has added a layer of confusion to the 2026 market. These are individuals who tie up your home with a contract and then try to sell that contract to a real investor for a fee. They often lack the funds to actually close. To protect yourself, watch for these specific red flags:
- Upfront Fees: A legitimate buyer will never ask you to pay for an application or an assessment fee.
- Vague Proof of Funds: Demand to see a recent bank statement or a letter from a reputable financial institution.
- The Bait and Switch: Be wary of buyers who offer a high price initially but then demand deep discounts after a 10-minute walkthrough.
A transparent partner will be honest about their numbers from the first conversation. They won’t pressure you into a decision before you’ve had time to review the contract. Reliability and honesty are the hallmarks of a professional transaction.
A Framework for Decision Making: Is a Cash Buyer Right for You?
Choosing the right path for your home sale isn’t about finding a universal “best” method. It’s about aligning the pros and cons of selling to a cash home buyer with your personal priorities. To find your answer, start by assessing your property’s condition. If your home requires more than $10,000 in structural or cosmetic repairs, the “as-is” benefit of a cash offer becomes significantly more valuable. In a 2026 market where buyers are cautious due to 6.87% mortgage rates, homes needing work often sit for months, accumulating taxes and utility bills that eat into your eventual profit.
Your timeline is the next critical factor. A traditional sale in the current climate typically takes 140 days or more from listing to funding. If you need liquidity in 14 days to settle a debt or move for a job, speed is your primary currency. Finally, analyze your equity. If you have a healthy cushion of ownership, you can afford to trade a small percentage of that equity for the total certainty of a closed deal. If you’re ready to see how the numbers look for your specific situation, you can request a transparent as-is evaluation to help guide your choice.
Scenario A: The Distressed Property or Situation
When a home faces code violations, hoarding issues, or major structural failure, it’s often unmarketable to traditional buyers who rely on bank financing. Banks simply won’t lend on properties they deem unsafe. In these cases, a cash buyer provides the only viable exit. This is also the most compassionate solution for those facing legal or financial deadlines. If you are struggling with a ticking clock, learning How to Sell a House in Pre-Foreclosure: A Compassionate 2026 Guide can provide a clear roadmap out of a stressful situation. A direct sale removes the public pressure of a foreclosure and protects your long-term credit.
Scenario B: The ‘Move-In Ready’ Home
If your home is in pristine condition, the pros and cons of selling to a cash home buyer shift. You might choose the traditional market to spark a bidding war among emotional buyers, potentially yielding a higher gross price. For sellers who prefer this route, you can discover The Kombrink Team to see how professional representation can help you achieve top dollar. However, we also see “convenience sales” from high-net-worth homeowners who value their privacy above all else. They choose a cash buyer to avoid the hassle of 20 different strangers walking through their bedrooms or the risk of a deal falling through at the eleventh hour. Transparency about your goals, whether they are financial or lifestyle-based, will always lead to the best outcome for your family.
Sometimes, a simple cash offer doesn’t quite bridge the gap between your financial needs and the property’s value. While we have explored the traditional pros and cons of selling to a cash home buyer, it is important to realize that cash is not the only tool available. Creative finance solutions offer a strategic middle ground. These methods allow you to achieve a higher sale price by moving beyond the constraints of a one-time lump sum payment. They are particularly effective in a 2026 market where traditional buyers are struggling with elevated mortgage rates.
Structures like “Subject-To” or seller financing are becoming increasingly common. In a “Subject-To” transaction, the buyer takes over the responsibility for your existing mortgage payments. This is particularly valuable if you have a low interest rate from years ago, as it allows the buyer to pay you more for the home than if they had to secure a new 6.87% mortgage. Seller financing, on the other hand, turns you into the “bank,” allowing you to receive monthly income plus interest. These innovative structures can solve complex title issues or debt hurdles that might otherwise stall a traditional sale, providing a path forward when the numbers don’t seem to add up.
Maximizing Value with Creative Exit Strategies
Creative finance is designed to be a partnership. For some sellers, receiving a steady stream of monthly income is more beneficial than a single lump sum, especially when considering the increased SALT deduction caps for 2026. By choosing Creative Real Estate Exit Strategies: A Homeowner’s Guide to Certainty in 2026, you can often secure a price much closer to a full market listing while still enjoying the speed and “as-is” convenience of an investor purchase. It provides a way to capture more of your home’s equity without the stress of an open-market listing or the fear of a deal falling through due to bank requirements.
Getting Your Fair Offer Today
At LPS Real Estate Group, we believe in “quiet confidence.” We don’t use high-pressure tactics because we know every homeowner’s situation is unique. Our role is to act as a compassionate expert, listening to your goals first and then presenting the options that make the most sense for your future. Whether a direct cash purchase or a creative finance structure is the right fit, we prioritize transparency in every contract. We explain the “how” and “why” behind every number so you feel fully informed. If you’re ready to explore your options without any pressure, you can Request your fair, transparent offer from LPS Real Estate Group today and take the first step toward a certain closing.
Move Toward Your Next Chapter with Clarity
Deciding how to sell your home is a deeply personal choice that depends on your property’s condition and your specific timeline. We have explored the pros and cons of selling to a cash home buyer, noting that while you might trade a portion of equity for speed, you gain the total certainty of a guaranteed closing. Whether you are navigating a complex probate situation or simply want to avoid the “inspection trap” of a traditional listing, there’s a path forward that respects your needs. You don’t have to face the 2026 market alone.
At LPS Real Estate Group, we specialize in as-is and probate buyouts with a transparent, no-fee closing process. If a standard cash offer doesn’t quite meet your goals, our expertise in creative finance solutions can help maximize your value without the stress of the open market. You deserve a partner who listens first and acts with integrity throughout the entire process. Ready to see what’s possible? Get Your Fair Cash Offer and Start Your Stress-Free Chapter Today. You have the power to choose the exit strategy that best serves your family’s future.
Frequently Asked Questions
Do I need to clean or repair my house before a cash buyer sees it?
No, you don’t need to lift a finger. We specialize in as-is property acquisition, which means we accept the home in its current state, regardless of debris, clutter, or structural damage. You can even leave unwanted furniture or trash behind. This is a major factor when weighing the pros and cons of selling to a cash home buyer. We handle the heavy lifting so you can focus on your move without the stress of cleaning.
How much do cash home buyers typically pay compared to market value?
Cash buyers typically offer between 5% and 15% below the full market value. This difference accounts for the convenience fee of a fast, certain closing without repairs or commissions. While the gross price is lower, your net proceeds are often comparable to a traditional sale because you avoid 6% agent fees and thousands in holding costs. Understanding the pros and cons of selling to a cash home buyer helps you see the true financial picture.
Are cash home buying companies legitimate or is it a scam?
Legitimate companies like LPS Real Estate Group are registered investment firms, but it’s vital to vet any buyer. Real investors will provide a clear proof of funds and won’t ask for upfront fees. Under the 2026 FinCEN reporting rules, professional buyers must disclose beneficial ownership for cash deals. This federal oversight adds a layer of transparency. Always check for a track record of ethical transactions and avoid high-pressure wholesale tactics.
Who pays the closing costs in a cash home sale?
In a direct cash sale, the buyer typically covers all closing costs, including title insurance and escrow fees. This is a significant departure from traditional listings where sellers often pay 1% to 3% in closing fees plus 6% in commissions. By removing these expenses, the process remains simple and transparent. You’ll know exactly what you’ll walk away with at the closing table without any hidden deductions or surprise bills.
Can I sell a house with a tenant or squatter to a cash buyer?
Yes, you can sell a property even if it’s currently occupied by tenants or squatters. Professional buyers specialize in handling these complex legal situations so you don’t have to. We take on the responsibility of managing the existing lease or the eviction process after the sale is complete. This allows you to liquidate the asset and walk away from the stress of a difficult property management situation immediately and safely.
What happens if I’m facing foreclosure—can a cash buyer really stop it?
A cash buyer can often stop a foreclosure by purchasing the home before the scheduled auction date. This process provides the funds necessary to pay off the lender in full, which halts the legal proceedings. It’s a compassionate solution that protects your credit and allows you to salvage your remaining equity. Acting quickly is essential, as lenders are more likely to cooperate when a certain closing is scheduled with a professional firm.
How quickly can I actually get the money after accepting a cash offer?
You can typically receive your funds within 7 to 14 days after accepting a formal offer. This speed is possible because cash transactions bypass the 30 to 60 day mortgage underwriting process required by banks. Once the title company completes a standard search and prepares the closing documents, the money is wired directly to your account. This rapid timeline provides immediate liquidity when you’re facing urgent financial or personal deadlines.
What documents do I need to provide for a direct property acquisition?
You primarily need to provide basic proof of ownership and a valid form of identification. If there’s an existing mortgage, you’ll need to share your most recent statement so the title company can request a payoff figure. For probate situations, you’ll also need the legal documents that authorize you to sell the estate. We guide you through each step of this direct property acquisition to ensure the paperwork is handled with care and accuracy.